
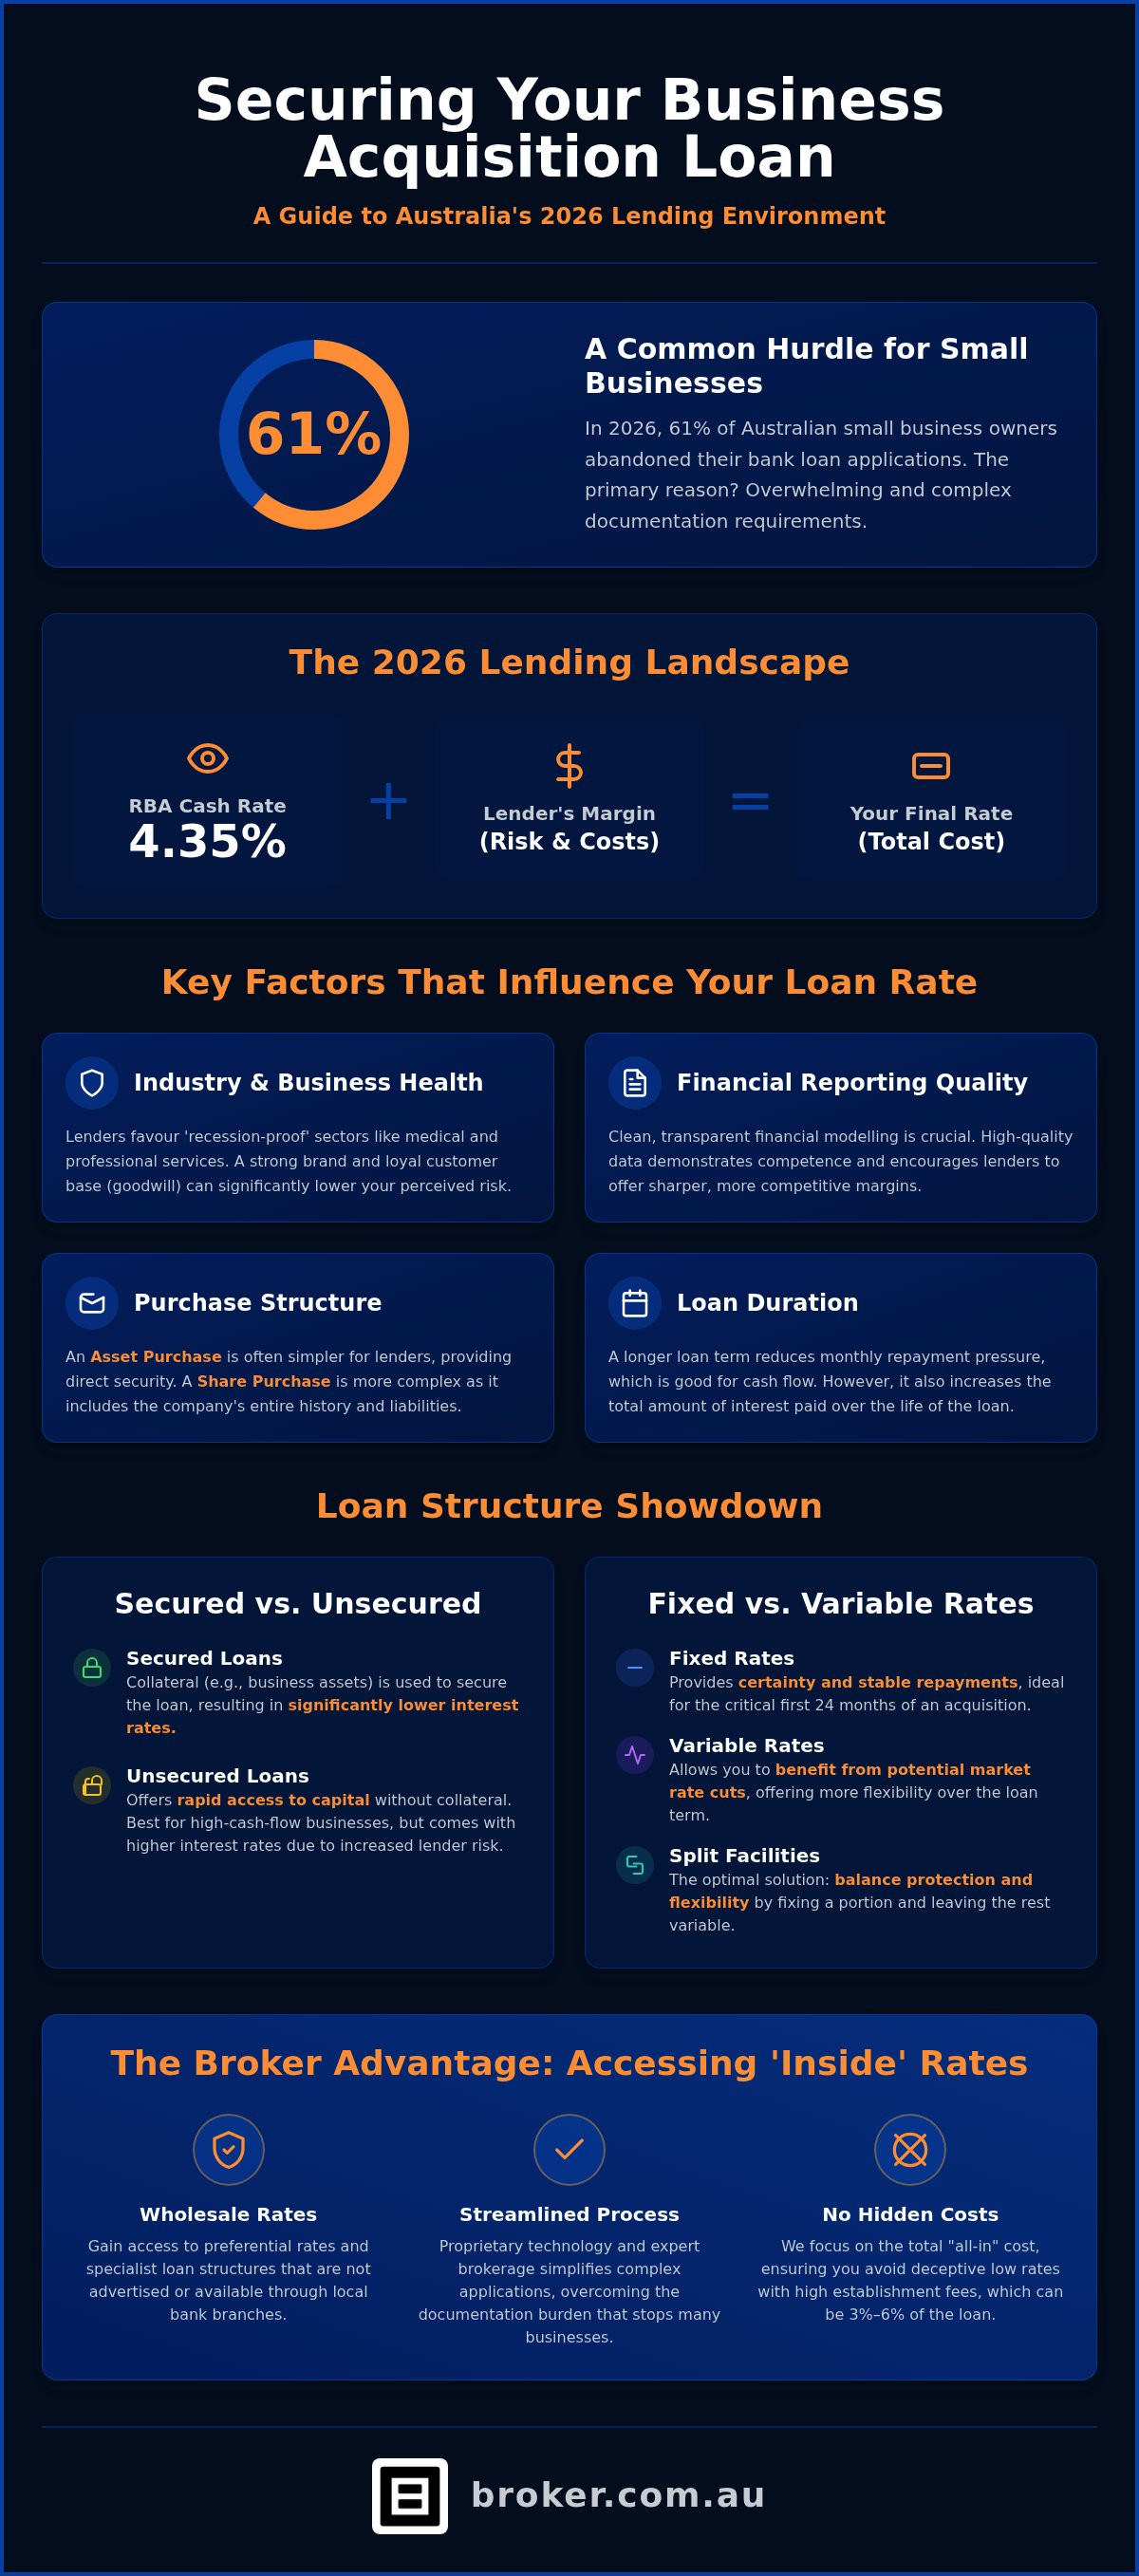
Did you know that 61% of Australian small business owners abandoned their bank loan applications in 2026 because the documentation requirements became too overwhelming? It’s a startling figure that highlights the gap between wanting to expand and actually securing the capital to do so. You might feel a similar sense of hesitation as you look at “indicator rates” that seem miles away from the actual figures landing on your desk. The stress of managing cash flow while facing potentially high repayments is enough to make any entrepreneur pause.
We understand that you aren’t just looking for a loan; you’re looking for a way to make your business dreams a reality without the sleepless nights. This guide reveals how to secure the most competitive interest rates in the current 2026 Australian lending environment, where the RBA cash rate sits at 4.35%. You’ll discover how a tailored business acquisition loan structure australia can unlock “inside” rates that aren’t advertised to the general public. We will walk you through the shift toward non-bank lenders and the latest regulatory changes, giving you a clear, stress-free path to funding your next big move with confidence.
Key Takeaways
- Understand how current economic conditions and the RBA cash rate directly influence commercial lending margins and your total acquisition costs.
- Learn to optimise your business acquisition loan structure australia by using professional financial modelling to lower your risk profile in the eyes of lenders.
- Compare the significant interest savings of secured funding against the rapid capital access provided by unsecured loan options for high-cash-flow businesses.
- Gain inside access to wholesale rates and specialist negotiation strategies that aren’t available through traditional local bank branches.
- Discover how proprietary technology and expert brokerage can streamline complex applications to ensure your funding path is both accurate and stress-free.
Table of Contents
- Understanding Business Purchase Loan Interest Rates in 2026
- Factors That Influence Your Acquisition Loan Rate
- Secured vs. Unsecured: How Collateral Impacts the Rate
- The ‘Broker Advantage’: Accessing Inside Rates
- Securing Your Funding with Broker.com.au
Understanding Business Purchase Loan Interest Rates in 2026
A business purchase loan interest rate is the cost of borrowing capital specifically to acquire an existing entity or its operational assets. In 2026, the Australian lending environment is shaped by a Reserve Bank of Australia (RBA) cash rate that has stabilised at 4.35%. This figure acts as the foundation for all commercial lending, but it’s rarely the rate you’ll see on a final contract. Lenders add a margin to this base to cover their operational costs and the perceived risk of the transaction.
The economic climate in 2026 has seen a shift in how banks view commercial margins. While the cash rate provides a floor, your final interest rate is influenced by liquidity in the Australian credit market and broader inflationary pressures. Many sophisticated buyers employ a Leveraged buyout (LBO) strategy, where the assets of the target company are used as collateral to secure the debt. Because this involves significant borrowed capital, even a minor variation in your business acquisition loan structure australia can lead to a substantial difference in total interest paid over the life of the loan.
The Components of a Commercial Interest Rate
Lenders don’t just pick a number out of thin air. They start with indicator rates, which are benchmark figures reflecting the cost of funds and market competitiveness across the financial sector. From there, they apply a risk margin based on your industry experience and the health of the business you’re buying. If you’re entering a volatile sector, expect a higher margin. Don’t overlook the fee structure either. A “low rate” can be deceptive if it’s paired with high establishment fees, which can range from 3% to 6% of the loan amount. At Broker.com.au, we focus on the “all-in” cost to ensure you aren’t caught out by hidden expenses.
Fixed vs. Variable Rates for Acquisitions
Choosing between fixed and variable rates depends on your appetite for risk and your cash flow requirements. Fixed rates offer absolute certainty during the critical first 24 months of an acquisition. This stability allows you to forecast repayments accurately while you integrate the new business. Variable rates, however, allow you to benefit if the Australian market experiences rate cuts. Many of our clients choose split facilities. By fixing a portion of the debt and leaving the rest variable, you balance protection against rate hikes with the flexibility to make extra repayments. How you design your business acquisition loan structure australia determines whether you can adapt to shifting market conditions without stifling your growth.
Factors That Influence Your Acquisition Loan Rate
Lenders in 2026 assess more than just your deposit. They scrutinise the ‘goodwill’ of the business you’re acquiring. While physical assets like machinery provide clear security, a strong brand name and loyal customer base represent intangible value that can actually lower your risk profile if documented correctly. This is where professional financial modelling becomes indispensable. By presenting clean, transparent data, you demonstrate a level of competence that encourages lenders to offer sharper margins. According to the Reserve Bank’s analysis of business lending, credit availability remains tied to the quality of financial reporting, making your preparation as vital as your profit margins.
Industry specialisation also plays a significant role. If you’re acquiring a medical practice or a professional services firm, you’ll likely access more competitive rates because these sectors are viewed as ‘recession-proof’ by major Australian banks. Your borrowing duration matters too. While a longer loan term reduces monthly repayment pressure, it increases the total interest paid over time. Balancing these factors is a core part of an effective business acquisition loan structure australia, ensuring your cash flow remains healthy during the transition. How you refine your business acquisition loan structure australia will ultimately dictate your monthly overheads.
Asset vs. Share Purchase Considerations
The legal structure of your purchase significantly impacts your lender’s security position. Buying just the assets allows a lender to register a direct interest in tangible equipment, which often results in a more straightforward approval process. Conversely, a share purchase involves taking over the entire company entity, including its history and potential liabilities. This added complexity can sometimes lead to interest rate variances. If you’re navigating these choices, we can help you explore a tailored business acquisition funding solution that balances security with your long-term tax objectives.
The Importance of a Strong Business Plan
A robust business plan is your primary tool for satisfying bank credit departments. You must clearly demonstrate a strong debt-service coverage ratio (DSCR) to prove the business can comfortably meet its repayments. Your personal credit history as the business owner also serves as a critical benchmark for the final commercial rate offered. In 2026, lenders increasingly weigh consistent historical EBITDA against rigorous three-year forward-looking projections to determine the sustainability of your acquisition.
Secured vs. Unsecured: How Collateral Impacts the Rate
Deciding between a secured or unsecured facility is a pivotal moment in designing your business acquisition loan structure australia. Secured loans involve pledging tangible assets to the lender, which significantly reduces their risk and, consequently, your interest rate. If you have commercial property or high-value business equipment to offer, you can drive your borrowing costs down to the lowest possible margins. For those who need capital quickly, unsecured loans offer a faster path for high-cash-flow businesses, though they carry higher rates to compensate for the lack of physical security. Referencing the government guide to business funding can help you understand the broader debt finance options available to Australian entrepreneurs in 2026.
Many buyers are tempted to use their personal residence to secure a business loan because residential-backed rates are often the most competitive in the market. However, we urge caution regarding this “home risk” approach. Tying your family home to a business purchase means that any operational downturn could directly impact your personal stability. A more sophisticated alternative is asset finance, where the equipment or vehicles you’re acquiring serve as the sole security. This keeps your personal and business wealth separate while still providing a professional funding solution that doesn’t put your family’s roof at risk.
Comparing Rate Benchmarks
Interest rate margins vary significantly based on the quality of your collateral and the lender’s security position. Consider these common benchmarks when weighing your options:
- Residential-backed: Offers the sharpest margins but requires personal property as collateral.
- Commercial-backed: Moderate rates using business premises or high-value assets like machinery.
- Unsecured: Higher interest rates but preserves your asset base and offers significantly faster approval times.
If you need flexibility post-acquisition, an unsecured line of credit can provide essential working capital without the need for additional property security. A General Security Agreement (GSA) is a legal document that grants a lender a security interest over all the assets of a business to guarantee loan repayment, which typically results in lower interest rates compared to purely unsecured funding.
Avoiding Cross-Collateralisation Pitfalls
A common mistake is allowing a single bank to hold the mortgage on both your home and your new business. Keeping these loans with separate lenders creates a strategic “firewall” that protects your personal wealth. This “clean” finance structure ensures that if the business faces challenges, the bank cannot automatically look to your home equity to cover the shortfall. Understanding the hidden risks of cross-collateralisation is essential for any buyer who values long-term financial security. By organising your debt across different institutions, you maintain greater negotiation power and ensure your family’s future remains in good hands.
The ‘Broker Advantage’: Accessing Inside Rates
Securing the most competitive funding isn’t as simple as walking into your local branch. Most Australian banks only list their “base indicator rates” on their websites, which are retail figures that rarely reflect the actual cost for a sophisticated borrower. We provide inside access to wholesale rates that aren’t available to the general public. By leveraging our relationships with over 30 lenders, we pit the “Big Four” against agile non-bank lenders to ensure you aren’t just getting a loan, but the most efficient capital available in the 2026 market.
A specialist broker acts as a “High-Level Fixer” for complex acquisitions. Whether your deal involves intricate M&A requirements or falls slightly outside of traditional lending criteria, we manage the heavy lifting. This includes handling the rigorous financial modelling and lender paperwork that often causes 61% of SMEs to abandon their applications. Optimising your business acquisition loan structure australia requires more than just a low rate; it needs a partner who understands how to present your data to credit departments to win a “Yes” on your terms.
Why One Bank is Never Enough
Lender appetite in Australia is constantly shifting. In 2026, a bank that was aggressive in the medical sector last month might change its credit policy tomorrow, leading to a sudden rejection of your application. This doesn’t mean your deal is flawed; it just means that specific bank’s internal “bucket” for that industry is full. We take a tailored approach rather than a one-size-fits-all product. Because we monitor these policy shifts in real-time, we know exactly which lender currently has the highest appetite for your specific industry and risk profile.
The Role of Advisory in Loan Restructuring
True value in an acquisition comes from expert debt structuring. Sometimes, a well-designed business acquisition loan structure australia can save you more money than a 0.5% interest rate cut ever could. We look at your entire footprint, integrating asset finance for equipment and fit-out finance for your premises into a single, cohesive strategy. This corporate advisory insight ensures your repayments are aligned with your projected cash flow. If you’re ready to discover how we can fast-track your funding, I’m interested in a stress-free conversation about your acquisition goals.
Securing Your Funding with Broker.com.au
Securing capital for a major purchase requires more than just a standard application form; it requires a sophisticated partner who understands the nuances of the Australian lending landscape. At Broker.com.au, we are an award-winning national broker dedicated to providing best-in-class finance solutions. By integrating proprietary AI technology into our workflow, we ensure your business acquisition loan structure australia is both accurate and fast-tracked to meet 2026 standards. We operate as your expert guide, moving you from a state of uncertainty toward a feeling of streamlined confidence. Our national reach means that whether you are acquiring a medical practice or a manufacturing hub, you receive elite, boutique-level attention that large-scale banks simply cannot replicate.
Our Seamless Application Process
The journey begins with a low-pressure conversation. Unlike the aggressive tactics often found at traditional banks, our “I’m interested” approach starts a dialogue focused on your specific needs and long-term dreams. We then utilise AI-enhanced data collection to significantly reduce the paperwork headache that often plagues busy SMEs. This technology allows our specialists to perform deep financial modelling quickly, ensuring your data is presented to lenders in the most professional light possible. Once your profile is ready, we match you with the top three competitive offers from our extensive panel of over 30 lenders. This process is designed to be efficient and professional, giving you a clear path to settlement with zero stress.
Get Started Today
In a shifting market, hesitation can be costly. Waiting for a potential rate drop might mean losing a prime business opportunity to a more prepared competitor who has already secured their finance. We provide a preliminary borrowing power assessment to give you a clear understanding of your capacity before you even sign a heads of agreement. This proactive stance ensures you are in good hands from the very first step. Our team, including experts like Matt and Kylie, is ready to go above and beyond for situations that fall outside of the norm. If you are ready to secure a tailored business acquisition loan structure australia, I’m interested in a business purchase loan. Our goal is to make the funding path as efficient as the business you are about to lead.
Take Control of Your Next Business Acquisition
Navigating the 2026 lending landscape requires more than just a passing glance at advertised interest rates. Securing the most competitive deal involves a deep understanding of how your business acquisition loan structure australia balances risk, security, and cash flow. Whether you’re leveraging assets to drive down margins or choosing an unsecured path for speed, the right strategy protects your personal wealth while fueling your professional growth. You’ve worked hard to find the right opportunity; don’t let a “one-size-fits-all” bank product stifle your momentum.
As an award-winning Australian broker, we provide inside access to over 30 leading lenders and utilise proprietary AI-powered application accuracy to ensure your funding path is seamless. We’re here to act as your expert guide, handling the complex financial modelling so you can focus on the transition. If you’re ready to move from uncertainty to streamlined confidence, we’re ready to help. I’m interested in exploring my finance options and taking the next step toward a successful settlement. Your business future is in good hands.
Frequently Asked Questions
What is a typical business purchase loan interest rate in Australia for 2026?
Secured business loan rates generally range from 6.8% to 9.5% p.a., while unsecured options typically sit between 9.5% and 18% p.a. as of late 2026. Major banks like CBA offer variable secured rates from 7.29% p.a. for loans from $10,000. Your specific rate depends on your business acquisition loan structure australia and the level of security provided. We use proprietary AI to help you navigate these margins and find the most efficient capital available.
Can I get a business loan to buy a franchise?
Yes, you can certainly secure funding for a franchise purchase through various business acquisition funding options. Lenders often view established franchise systems more favourably because they have proven business models and historical performance data. Approval depends on the franchisor’s reputation and your personal experience. We specialise in tailoring finance for these models, ensuring your application highlights the strength of the brand alongside your professional capabilities for a stress-free outcome.
Do I need a deposit for a business purchase loan?
Most lenders require a deposit or equity contribution, typically ranging from 20% to 50% of the purchase price. However, if you have existing commercial or residential property to use as security, you may be able to borrow a higher percentage of the total value. The specific requirement often hinges on your business acquisition loan structure australia. We help you explore ways to leverage your current assets to minimise the cash deposit needed for settlement.
How does an SMSF loan work for buying commercial property?
An SMSF loan uses a Limited Recourse Borrowing Arrangement (LRBA) to allow your super fund to purchase business real property. As of August 2026, new LRBAs are strictly limited to acquiring business-related real estate. The property is held in a separate trust until the loan is fully repaid, protecting the rest of your fund’s assets. This is a specialised area of finance where our expert guides provide the technical modelling required for compliance and long-term security.
Is it better to have a fixed or variable rate when buying a business?
The choice depends on whether you value repayment certainty or flexibility in the shifting 2026 market. Fixed rates provide stable repayments during the critical first two years of an acquisition, protecting you from potential rate hikes. Variable rates allow you to benefit if the RBA cuts the cash rate below 4.35%. Many owners choose a split facility to balance these risks. We help you decide based on your specific cash flow projections and risk appetite.
How long does it take to get a business purchase loan approved?
Approval times vary between 24 hours for simple unsecured loans and several weeks for complex secured acquisitions. While 61% of SMEs abandoned bank applications in 2026 due to documentation delays, our AI-powered process fast-tracks the collection of essential data. By presenting a professional, audit-ready package to our panel of over 30 lenders, we aim to move you from “I’m interested” to a formal approval as efficiently and seamlessly as possible.
What documents do I need to provide for a business acquisition loan?
You generally need two years of financial statements for the target business, including profit and loss statements and balance sheets. Lenders also require your personal tax returns, a detailed business plan, and cash flow projections. Providing clean, professional data is essential for securing sharper rates. Our team assists with the financial modelling required to satisfy credit departments, making the complex application process feel manageable and transparent for busy entrepreneurs and business owners.
Can I use my home as security for a business loan?
Yes, using residential property as security often allows you to access lower interest rates and higher borrowing limits. However, this “home risk” approach links your personal residence to the success of the business. We often suggest exploring alternative business acquisition loan structure australia options, such as asset finance or separate commercial facilities. This strategic separation helps protect your family home while still providing the essential capital needed to fund your acquisition and growth.
