Across Australia, a quiet shift is under way. Thousands of business owners who built their companies through the 1980s, 1990s and 2000s are reaching the point where they want to step back. Many of them run profitable, well-established businesses with loyal customers, experienced staff and solid reputations. And many of them have no clear plan for who will take over.
For the right buyer, this is one of the most significant opportunities in a generation. Good businesses are coming to market, and owners are often more open to flexible deal terms than they would have been ten years ago. The challenge is knowing how to find the right business, how to fund it properly, and how to get the deal across the line without costly mistakes.
This article looks at why 2026 is shaping up as a turning point for business acquisition in Australia, and why the advisers you choose can make the difference between a smooth handover and a deal that falls over.
A generation ready to step back
Australia’s baby boomers, born between 1946 and 1964, are now aged roughly 62 to 80. This generation built a large share of the country’s small and medium businesses. They started trades businesses, manufacturing operations, wholesale distributors, professional practices, transport companies and service firms that still form the backbone of local economies today.
The scale of what they own is significant. According to the Australian Bureau of Statistics, there are more than 2.5 million actively trading businesses in Australia (: This is approximate, based on ABS Counts of Australian Businesses), and the vast majority are small businesses with fewer than 20 employees. Small business also employs around five million Australians (estimate), which makes the question of who owns these businesses next a national economic issue, not just a personal one for each owner.
The Productivity Commission has estimated that around $3.5 trillion in wealth will be transferred between generations in Australia between 2021 and 2050. A meaningful portion of that wealth sits inside privately owned businesses. Unlike a house or a share portfolio, a business can’t simply be handed over in a will and keep running. It needs a new owner who can lead it.
The succession gap
Here is the problem. Many owners have spent decades working in their business and very little time planning their exit from it.
[Insert verified succession planning statistic, e.g. the share of SME owners without a formal succession plan, with source.]
In practice, we see the same story again and again. An owner in their sixties has a business turning over several million dollars a year. Their children have built careers elsewhere and have no interest in taking it on. There is no second-in-charge ready to buy them out. The owner knows they need to sell, but they have put it off because the business still needs them every day.
When owners leave it too late, the outcomes can be poor. Some sell under pressure because of health issues or burnout. Some close their doors altogether, and with them go jobs, supplier relationships and decades of goodwill. Others hand the keys to a buyer who isn’t properly funded, and the business struggles within a year or two.
None of these outcomes are good for the owner, the staff or the community. And all of them point to the same opportunity: there are far more good businesses that need new owners than there are prepared, well-advised buyers ready to take them on.
Why this is an intergenerational opportunity
For younger operators, managers and existing business owners, the next few years offer something that doesn’t come around often. A large number of established, cash-flowing businesses will change hands within a relatively short period.
Buying an existing business has clear advantages over starting from scratch. You inherit a trading history, a customer base, systems, staff and supplier relationships. You can see what the business has earned over several years, rather than relying on projections. And in many cases, the outgoing owner is willing to stay on for a transition period to introduce you to key clients and help keep the team steady.
Owners who are motivated to retire are often open to creative structures as well. Vendor finance, where the seller agrees to be paid part of the price over time, is a common example. So are earn-outs, where part of the price depends on the business hitting agreed targets after the sale. These structures can reduce the amount of cash a buyer needs upfront and give both sides confidence that the business will continue to perform.
There is also a broader point. The people who buy these businesses over the next decade will shape a large part of Australia’s private economy for the next thirty years. Second-generation and next-generation owners who bring fresh energy, better technology and new markets can take a solid business and make it a great one. That is what makes this moment so important. It is not just a transfer of assets. It is a transfer of responsibility and potential from one generation of business builders to the next.
What makes a good business worth buying
Not every business for sale is a good business, and not every good business is right for every buyer. Before thinking about finance, buyers should be clear on what they are looking for.
Strong business acquisition targets usually share a few traits. They have consistent, verifiable earnings over several years. They aren’t overly dependent on the owner personally, or if they are, there is a realistic plan to transfer those relationships. They have a spread of customers rather than one or two accounts making up most of the revenue. They have reasonable equipment, clean financial records and no major legal or tax issues hiding in the background.
Buyers should also be honest about their own skills and capacity. A profitable business in an industry you don’t understand can quickly become a problem. The best acquisitions tend to happen when the buyer brings relevant experience, management ability or strategic fit, such as an existing business owner buying a competitor or a complementary operation.
Funding the deal: why loan structure matters
Once you have found the right business, the next question is how to pay for it. This is where many buyers underestimate the complexity.
Business acquisition finance is different from a home loan. Lenders look closely at the business’s historical earnings, its ability to service the debt from cash flow, the buyer’s experience, the security available and the amount of equity the buyer is contributing. Lenders commonly expect buyers to put in a meaningful contribution of their own, though the exact amount varies widely depending on the lender, the industry and the strength of the deal.
A well-structured acquisition loan often involves more than one component. There may be a term loan for the purchase price, an overdraft or working capital facility to keep the business running smoothly after settlement, and equipment finance for plant, vehicles or machinery. Where property is involved, there may be a separate commercial property loan. Vendor finance might sit alongside bank debt and needs to be documented properly so that every party understands their position.
Getting this structure wrong can be expensive. A loan with repayments that are too tight can starve the business of cash in its first year, just when the new owner needs room to settle in. Security arrangements that are too broad can put the buyer’s family home at greater risk than necessary. A facility that doesn’t allow for working capital needs can leave the business unable to pay suppliers or staff during seasonal dips.
This is why the choice of finance adviser matters. A specialist business finance broker understands how different lenders assess acquisition deals, which lenders are active in which industries, and how to present a deal so that it has the best chance of approval on sensible terms. They can compare options across banks and non-bank lenders, negotiate on structure as well as rate, and help the buyer understand the trade-offs before signing anything.
The team around the deal
Finance is only one part of a successful acquisition. Buying a business involves legal, tax, accounting and commercial questions that need expert input.
A good commercial lawyer will review the sale contract, advise on the right structure for the purchase, check leases and key supplier or customer agreements, and protect the buyer through warranties and indemnities. An experienced accountant will review the financial statements, test the earnings being presented, identify any tax issues and advise on how the buying entity should be set up. Depending on the deal, the buyer may also need input from a business valuer, an insurance adviser or an industry specialist.
The difficulty for many buyers is that they don’t already have these relationships in place, or their existing advisers don’t specialise in acquisitions. A broker adviser who works on acquisition deals regularly can introduce buyers to lawyers and accountants who know this type of work well. That introduction alone can save weeks of delay and help avoid mistakes that only show up after settlement.
Just as importantly, a broker adviser can help coordinate the process. Acquisitions involve many moving parts: due diligence, lender approval, contract negotiation, lease assignment, staff transfer and settlement timing. When the finance adviser, lawyer and accountant are working together and communicating clearly, the deal moves faster and with fewer surprises.
How Broker.com.au helps buyers through the process
At Broker.com.au, business acquisition finance is a core part of what we do. This year, we have successfully settled multiple business acquisitions for clients, guiding them from the early stages of assessing a target business right through to settlement day.
Real Client Acquisition
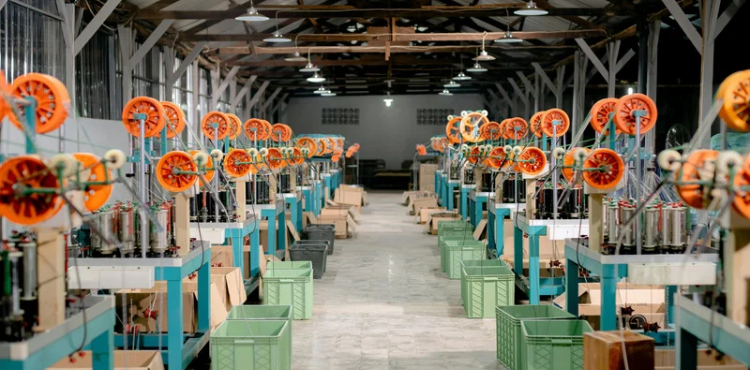
John*(not real name) had a wealth of experience in the machinery maintenance space, and was looking to acquire a business that manufactures blinds/awnings machines – ie, the machines that make bonds and awnings. The perfect sponsor with relevant background & experience. Scenario:
- Acquisition Price = $2,200,000
- Cash Contribution = $1,000,000
- Property Collateral Equity $200,000
- Acquisition Loan of $1,200,000 – meaning $1m was unsecured, $200k secured by property
The Problem
- Our client went to a big 4 bank himself. Banker said it would get done, then got declined by credit
- Client went to a broker – broker said they could do it. Then it got declined by bank.
- Client came to Broker.com.au and had lost 4 months already from the banker and previous broker
The solution
- Broker.com.au team went through a thorough internal due diligence process with the client
- We created: due diligence report, cash flow forecast, borrower statement, 3-way working model, presented the lender with deal risk and also risk mitigation
The Result
- Broker.com.au got this acquisition settled for the client with bank funding
- We did what others could not achieve
Our approach is practical and hands-on. We start by understanding the buyer’s goals, experience and financial position, and the business they want to buy. We review the numbers with a lender’s eye, so the buyer knows early whether the deal is fundable and what a realistic structure looks like. We then approach the lenders best suited to that deal, negotiate terms and help prepare the information lenders need to make a decision.
Where clients need it, we introduce trusted partners, including lawyers and accountants who are experienced in business acquisitions. We work alongside these advisers throughout the deal so that finance, legal and accounting advice all point in the same direction.
We have seen firsthand how complex these transactions can be. Contracts change, due diligence uncovers questions, lenders ask for more information and timelines shift. Having an adviser who has been through this process many times helps buyers stay calm, make good decisions and keep the deal moving.
Practical steps for buyers in 2026
If you are thinking about buying a business in the next year or two, there are a few things you can do now to put yourself in a stronger position.
First, get clear on what you want to buy and why. Define the industry, size, location and type of business that suits your skills and goals.
Second, understand your borrowing capacity before you start making offers. Speaking to a business finance broker early will tell you what size of deal is realistic and how much equity you are likely to need.
Third, build your advisory team before you need it. Having a lawyer and accountant lined up means you can move quickly when the right opportunity appears.
Fourth, be prepared to look beyond advertised listings. Many good businesses are sold quietly through business brokers, accountants and industry contacts. Letting your network know what you are looking for can open doors.
Finally, take your time with due diligence. A motivated seller is a good thing, but it is not a reason to skip proper checks. The best deals are the ones where both sides go in with their eyes open.
A moment worth acting on
Australia is entering a period where a large number of established, profitable businesses will need new owners. For the owners stepping back, a well-planned sale means a fair price, a secure retirement and a business that continues to support its staff and customers. For buyers, it is a chance to take over something that already works and build on it.
Opportunities like this don’t stay open forever. The buyers who do best will be the ones who are prepared, properly funded and well advised. With the right finance structure and the right team around them, the next generation of Australian business owners can turn this handover into one of the best decisions they ever make.
If you are considering buying a business, Broker.com.au can help you assess the opportunity, structure the right acquisition loan and connect you with the advisers you need to complete the deal with confidence.