Why wait five years to double your revenue through organic growth when a strategic business acquisition could achieve it in five months? For many Australian SME owners, the path to expansion feels blocked by complex bank jargon and the fear of risking the family home. You’re likely searching for how to get a loan to grow your business, yet the reality of slow approval times often means missing out on lucrative opportunities. It’s a common frustration when traditional lenders move at a glacial pace.
We believe securing finance should feel like a partnership, not a hurdle. This guide provides a clear roadmap to growth finance, specifically focusing on how Business Acquisition Funding can scale your operations faster than traditional methods. You’ll discover the essential requirements for a business buyer in 2026, from cash flow modelling to acquisition finance structures. We also preview how a streamlined, AI-driven process for buying a business provides inside access to the best rates, ensuring you move from uncertainty to professional confidence. By the end of this guide, you’ll have the insights needed to navigate the lending landscape and secure the funding your next big move demands.
Key Takeaways
- Understand why a strategic business acquisition is the fastest path to market dominance, offering instant access to established cash flow and operational systems.
- Learn the specific steps for how to get a loan to grow your business, focusing on the difference between operational working capital and strategic growth finance.
- Gain clarity on the deposit and equity requirements for acquisition finance to ensure your application is best in class for Australian lenders in 2026.
- Discover how a business buyer can leverage proprietary AI and broker insights to find tailored funding solutions that fall outside of standard banking criteria.
- Identify the most efficient funding structures for buying a business to manage the opportunity cost of waiting, allowing you to scale without risking the family home.
Table of Contents
- Understanding Your Growth Finance Options in the Australian Market
- Buying a Business: Why Business Acquisition is the Ultimate Growth Strategy
- Comparing Acquisition Finance, Unsecured Loans, and Working Capital
- Step-by-Step: How to Prepare Your Acquisition Loan Application
- Navigating the Australian Lending Landscape with an Expert Broker
Understanding Your Growth Finance Options in the Australian Market
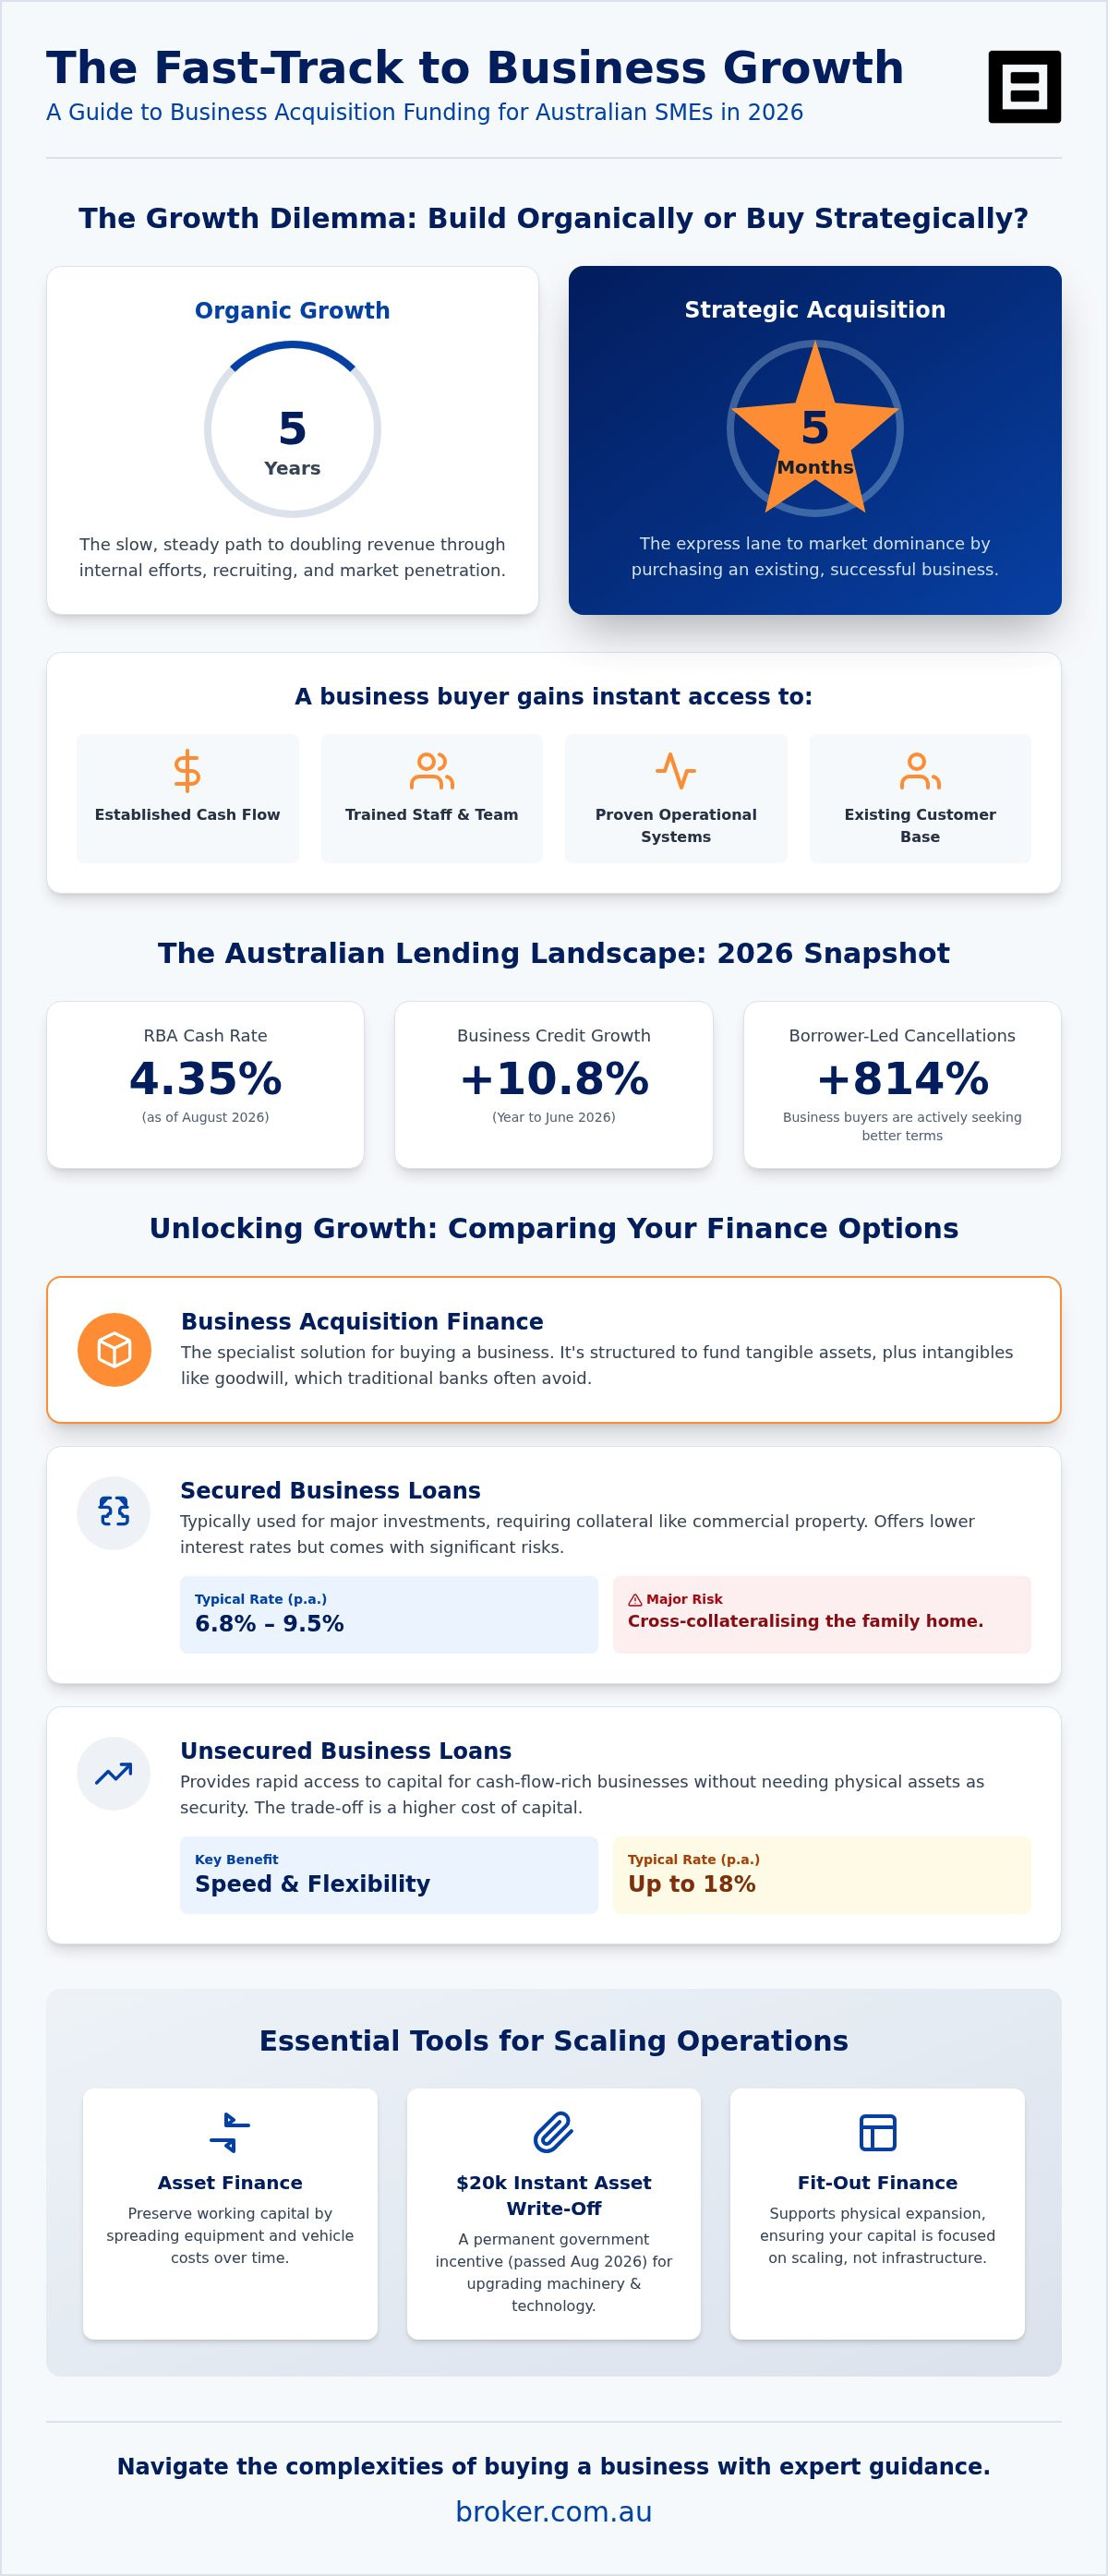
Growth finance is the intentional deployment of capital to capture market share, increase capacity, or scale revenue. While working capital keeps your business running, growth finance is the fuel for strategic expansion, often achieved through a strategic business acquisition. If you are looking for how to get a loan to grow your business in 2026, you’ll find the Australian lending landscape is increasingly complex. With the RBA cash rate at 4.35% as of August 2026, the cost of capital has shifted, making the role of an expert guide essential. Traditional banks often struggle to keep pace with fast-moving SMEs, relying on rigid criteria that don’t account for your unique growth potential.
Securing the right capital involves more than just an application; it requires a strategic understanding of the market. Understanding business loan structures is the first step in determining how to get a loan to grow your business without compromising your long-term stability. Many owners find themselves trapped in bank queues, only to be met with requirements that don’t align with their timeline. Tailored solutions provide the inside access needed to bypass these institutional bottlenecks, particularly when pursuing Business Acquisition Funding to scale rapidly.
The 2026 market shows a significant shift in borrower behaviour. Recent data indicates that borrower-led loan application cancellations increased by 814% in the June 2026 quarter. This suggests that savvy Australian business owners are no longer settling for the first offer they receive. They are actively seeking better terms and more flexible structures that traditional institutions often fail to provide. By looking beyond standard bank products, you can find finance that actually supports your trajectory while ensuring your application remains best in class.
The Difference Between Secured and Unsecured Growth Loans
Secured loans typically offer lower interest rates, ranging from 6.8% to 9.5% per annum in late 2026. These require collateral, such as commercial property, to back the debt. Unsecured business loans provide speed for cash-flow-rich enterprises, though rates can reach 18%. A major risk is cross-collateralisation, where a lender uses your family home to secure business debt. We prioritise structures that protect your personal assets while delivering growth capital through a stress-free process.
Asset Finance and Equipment Leasing for Scaling Operations
Asset finance allows you to preserve working capital by spreading equipment costs over time. The permanent $20,000 instant asset write-off, passed in August 2026, is a vital tool for upgrading technology or machinery. Using a chattel mortgage provides specific tax benefits as you own the asset from day one. Fit-out finance also supports physical expansion, ensuring your capital remains focused on scaling rather than being tied up in property improvements or infrastructure costs.
Buying a Business: Why Business Acquisition is the Ultimate Growth Strategy
Scaling through organic growth is often a slow burn. A savvy business buyer knows that purchasing a competitor or a complementary firm is the fastest route to market dominance. In the 2026 Australian economy, where business credit grew by 10.8% in the year to June, capital is being deployed with greater strategic intent. Instead of spending years recruiting talent and building a customer base, buying an existing business provides instant access to trained staff and proven operational systems. This “buy vs build” approach is frequently the most efficient answer when considering how to get a loan to grow your business.
Traditional banks often hesitate when funding intangible assets like goodwill. This is where specialised Business Acquisition Funding becomes critical. While specific government initiatives, such as the Business Loan Package for Indigenous-owned enterprises, offer targeted support, the broader SME market requires tailored private solutions. These facilities are designed to bridge the gap between your available equity and the total purchase price, ensuring a seamless transition of ownership without stalling your momentum.
Success in this space requires more than just a balance sheet. It demands a sophisticated understanding of how a new entity fits into your existing structure. If you are looking to accelerate your timeline, you can start a conversation with our specialists to explore how strategic finance can unlock these opportunities.
The Role of Acquisition Finance in Your Growth Plan
Acquisition finance is a unique tool because it accounts for the future earnings and established reputation of the target business, not just its physical machinery. This is a core component of understanding how to get a loan to grow your business through acquisition. Structuring these deals usually involves balancing your deposit with the seller’s valuation. By utilising professional financial modelling, you can demonstrate to lenders that the combined entity’s cash flow will service the debt more effectively than the standalone businesses could on their own.
Key Considerations for the Modern Business Buyer
Every business buyer must identify “synergy”-the specific way two companies create more value together than they do apart. Lenders look for these operational efficiencies during the application process to mitigate risk. Beyond the numbers, high-level corporate advisory helps you navigate the complexities of M&A. It’s about finding an expert guide who can handle the “outside of the norm” scenarios that traditional banks often reject. This proactive approach ensures your growth remains stress-free and professional.
Comparing Acquisition Finance, Unsecured Loans, and Working Capital
Selecting the right financial instrument is a critical decision for any business buyer. While your expansion strategy might be clear, the funding must align with specific growth milestones to be effective. For instance, acquisition finance is tailored for the purchase of established entities, whereas unsecured business loans might suit a rapid inventory boost. If you’re researching how to get a loan to grow your business, the primary hurdle isn’t just the interest rate; it’s the opportunity cost of waiting. In the 2026 market, where business credit demand remains high, delaying a strategic purchase could mean losing a prime competitor to another firm.
Traditional banks often present a limited menu of standard products. We act as a high-level fixer, using proprietary AI technology to compare rates across a national panel of over 80 lenders. This provides inside access to competitive terms that aren’t available to the general public. Our process is designed to be stress-free, moving you from the complexity of financial modelling to a streamlined approval. By comparing different facilities side-by-side, you can ensure your capital structure is efficient and professional.
Understanding the nuances of each loan type is vital. A business buyer must weigh the cost of capital against the projected return on investment. While some facilities offer lower rates, they may require more significant collateral or longer approval times. Our role is to find the “outside of the norm” solution that fits your timeline and goals. This ensures you aren’t just getting a loan, but the right loan for your specific growth trajectory.
When to Choose a Line of Credit
A line of credit offers a flexible safety net during expansion phases. Unlike a standard business loan, you only pay interest on the funds you actually use. It’s often more efficient than a traditional business overdraft because it provides higher limits and more structured repayment terms. This revolving credit ensures you can manage fluctuating costs without reapplying for finance every time a new opportunity arises. It is an ideal tool for managing the bridging costs often associated with a business acquisition.
Invoice Finance: Unlocking Growth from Within
Invoice finance turns your outstanding accounts receivable into immediate liquidity. For a savvy business buyer, this can be a game-changer. You can use your existing ledger to fund a business acquisition, providing the deposit needed without tapping into your primary cash reserves. Modern platforms integrate seamlessly with your accounting software, making the transition professional and efficient. It’s a smart way to scale your operations using the value already locked inside your business, effectively funding your next move with your own success.
Step-by-Step: How to Prepare Your Acquisition Loan Application
Securing approval for a business acquisition demands precision. While earlier sections defined growth finance, the application stage is where your strategy meets lender scrutiny. Understanding how to get a loan to grow your business in 2026 means moving beyond basic tax returns to provide a comprehensive view of the future entity. This requires a disciplined approach that positions you as a sophisticated business buyer. By following a structured roadmap, you can transform a complex financial need into a streamlined path to resolution.
- Step 1: Conduct thorough due diligence on the target business, identifying risks in customer concentration or key staff contracts.
- Step 2: Understand your equity and deposit requirements to determine your actual borrowing capacity.
- Step 3: Prepare a robust business plan and cash flow forecast using professional financial modelling.
- Step 4: Demonstrate servicing capacity by showing exactly how the combined entity will handle debt obligations.
- Step 5: Partner with a specialist broker to access tailored solutions and inside access to the best rates.
If you’re ready to move forward, you can get started with our expert team for a tailored assessment of your acquisition plans.
Deposit and Equity Requirements for Business Buyers
Australian lenders generally expect a business buyer to have “skin in the game.” For a business acquisition, this typically translates to a deposit or equity contribution of 20% to 40% of the purchase price. However, you don’t always need cash sitting in a bank account to secure finance. Many successful buyers leverage existing business equity or commercial property to fund the new acquisition. In 2026, we are seeing more creative structures, such as vendor finance or earn-out arrangements, used to bridge the gap between your available equity and the total cost. These tailored solutions ensure your growth isn’t stalled by a lack of upfront liquidity.
Servicing and Cash Flow: What Lenders Really Look For
Lenders evaluate your application through the lens of the Debt Service Coverage Ratio (DSCR). This metric measures your ability to use the combined cash flow of both businesses to cover debt obligations comfortably. Most Australian lenders look for a DSCR of at least 1.25x to 1.5x, meaning your net operating income should be 25% to 50% higher than your annual debt payments. Presenting this requires professional financial modelling that accounts for synergies and cost savings after buying a business. Because these situations are often complex, an expert presentation is essential to move your application from uncertainty to a stress-free approval.
Navigating the Australian Lending Landscape with an Expert Broker
Approaching a single bank often limits your expansion to a narrow set of products designed for the average consumer. For a growth-minded SME, this restriction can be a significant bottleneck. A national broker acts as a seasoned partner, providing a broader perspective across a vast panel of lenders to find the specific structure your business requires. When you’re determining how to get a loan to grow your business, this breadth of choice is essential. We use proprietary AI technology to ensure your application is best in class, precisely matching your financial profile with the lenders most likely to offer favourable terms. This technology accelerates the process, allowing you to move with the speed the 2026 market demands.
The emotional weight of high-stakes financial decisions can be overwhelming for even the most experienced entrepreneurs. Our role is to alleviate that anxiety, moving you from a state of uncertainty toward streamlined confidence. We believe you should feel you’re in good hands throughout the entire journey. For a busy owner, a stress-free process isn’t just a preference; it’s a necessity that allows you to remain focused on your core operations while we handle the technical complexities of the lending landscape. Our proactive approach ensures that even situations falling outside of the norm are managed with professional authority.
The Broker.com.au Difference: Inside Access to Best Rates
Accessing non-bank lenders and private capital is often the key to unlocking growth that traditional institutions overlook. As a high-level fixer, we specialise in complex scenarios, including debt restructuring and tailored Business Acquisition Funding. This inside access to the best rates provides a competitive advantage that most business buyers cannot obtain on their own. We go above and beyond for Australian entrepreneurs, combining the technical expertise of a large-scale firm with the personal attention of a boutique advisory. Whether you’re navigating M&A complexities or seeking working capital, our insights ensure your finance is as scalable as your future plans.
Get Started: Your Path to a Scalable Future
We understand that every growth journey begins with a vision. That’s why we prioritise a low-pressure conversation over aggressive sales tactics. We want to hear about your specific needs and help you understand how to get a loan to grow your business without the typical banking friction. Our unique “I’m interested” approach is designed to be the first step in a supportive partnership, helping you transition from your current state to your ultimate growth dream with relief and clarity. If you’re ready to explore what’s possible, I’m interested in exploring my growth finance options and taking the next step toward a more professional, efficient, and successful enterprise.
Take the Next Step Toward Market Dominance
Mastering growth finance is the defining factor between a stagnant enterprise and a market leader. By now, you understand that a strategic business acquisition offers a significantly faster route to scaling than organic growth alone. Success in this landscape requires more than just a balance sheet; it demands a professional approach to due diligence and robust financial modelling. When you’re researching how to get a loan to grow your business, remember that traditional banks often lack the flexibility required for high-stakes acquisitions.
As an award-winning Australian brokerage, we provide the expert guidance needed to navigate these complexities. Our proprietary AI-driven application process ensures your file is best in class, while our inside access to 50+ Australian lenders unlocks rates you simply can’t find on your own. We handle the technical hurdles so you can focus on your vision. If you’re ready to move from uncertainty to streamlined confidence, we’re here to ensure you’re in good hands.
I’m interested in growing my business
Your growth dream is within reach, and with the right partner, the process is stress-free and efficient. Let’s start building your legacy today.
Frequently Asked Questions
How much can I borrow for a business acquisition in Australia?
Borrowing capacity depends on the target’s net profit and your existing equity. Generally, a business buyer can secure finance for 60% to 80% of the purchase price, including goodwill. For larger acquisitions, we use detailed financial modelling to demonstrate servicing capacity. High-level fixers can often secure higher limits by restructuring existing debt or leveraging commercial property. Every situation is unique, so we tailor the loan amount to your specific growth dream.
Do I need to put my house up as security for a growth loan?
Not necessarily. While secured loans offer lower rates by using property as collateral, unsecured business loans allow you to access capital based on cash flow alone. This approach helps you avoid cross-collateralisation, ensuring your family home isn’t at risk. If you’re wondering how to get a loan to grow your business without property security, we provide inside access to non-bank lenders who prioritise your business’s performance over personal assets.
What is the difference between secured and unsecured business loans?
The primary difference lies in collateral and cost. Secured loans require assets like commercial property or equipment, resulting in lower interest rates, typically between 6.8% and 9.5% in 2026. Unsecured business loans don’t require specific collateral but carry higher rates, often reaching 18%, because the lender takes on more risk. Unsecured options are generally faster to approve, making them ideal for businesses with strong cash flow needing immediate working capital.
How long does it take to get a business loan approved in 2026?
Approval times vary by loan type and complexity. Simple unsecured business loans can be approved within 24 to 48 hours using our proprietary AI technology. However, complex Business Acquisition Funding typically takes two to four weeks. This timeline allows for thorough due diligence and valuation of assets. Partnering with an expert broker ensures your application for how to get a loan to grow your business is best in class from the start.
Can I use my SMSF to help grow my business or buy property?
Yes, you can use a Self-Managed Super Fund (SMSF) to purchase commercial property that your business then leases. This is a common strategy for Australian entrepreneurs to build wealth while securing their business’s physical location. While SMSF loans have strict regulatory requirements and cannot be used for general business working capital, they’re a powerful tool for asset acquisition. We provide specialist expertise to guide you through these complex ATO regulations.
What documents do I need to prepare for an acquisition finance application?
Lenders require a comprehensive documentation pack to assess your application. You’ll need to provide:
- Two years of financial statements and tax returns for both entities.
- A detailed business plan and professional cash flow forecast.
- The Contract of Sale and comprehensive due diligence reports.
- Personal financial statements for all directors and stakeholders.
Having these ready ensures a seamless, professional application process and gives you inside access to the best available rates.
Is it better to grow organically or through buying a business?
Organic growth is a stable but slow process. In contrast, buying a business provides instant access to established customers, staff, and revenue streams. In the 2026 Australian market, acquisition is often the faster path to market dominance for SMEs with the right capital structure. While it requires more upfront investment, the opportunity cost of waiting for organic growth often outweighs the expense of acquisition finance. We help you evaluate which path suits your dream.
How does a business loan broker differ from a bank manager?
A bank manager can only offer products from their specific institution, which often leads to a rigid approach. As an award-winning broker, we provide inside access to a national panel of over 50 lenders, including non-bank and private capital. We act as a high-level fixer, tailoring solutions that fall outside of the norm for traditional banks. Our proprietary AI and corporate advisory services ensure you receive the most efficient, competitive finance for your needs.