
What if the weight of your ATO obligations and fragmented repayments isn’t a sign of a failing business, but simply a signal that your debt structure has been outpaced by the market? You’re likely feeling the daily friction of managing multiple repayment dates and the high costs of short-term, unsecured funding. It’s a common stress in the current climate, where over 14,000 Australian companies faced insolvency last financial year. You’ve worked too hard to let fragmented liabilities stifle your momentum.
This 2026 strategic guide introduces advanced business cash flow solutions australia designed to move you from financial complexity to streamlined confidence. You’ll learn how to restructure your liabilities, clear pressing tax debt, and unlock working capital using our proprietary AI lending strategies. We’ll show you how to secure a single, manageable monthly repayment and lower your interest costs, ensuring you’re in good hands as you scale your operations in an evolving economy.
Key Takeaways
- Simplify your financial management by consolidating fragmented liabilities into a single, professional facility with one manageable monthly repayment.
- Discover strategic methods to clear Australian Taxation Office (ATO) debt, helping you avoid escalating penalties and protecting your company from insolvency risks.
- Identify the most effective business cash flow solutions australia by comparing the flexibility of unsecured loans against the lower interest rates available through secured funding.
- Learn how to perform a comprehensive audit of your current liabilities and serviceability to prepare your business for a successful debt restructure.
- Understand how proprietary AI technology and expert corporate advisory can provide inside access to tailored rates across a panel of over 70 lenders.
Table of Contents
- Understanding Business Debt Consolidation in the Australian Market
- Effective Business Cash Flow Solutions Australia: Consolidation Options
- Comparing Secured vs. Unsecured Consolidation Strategies
- The Roadmap to Consolidating Your Business Debt
- Why a Strategic Broker is Your Best Asset for Cash Flow
Understanding Business Debt Consolidation in the Australian Market
Australian businesses are currently operating in a high-pressure environment. With the RBA cash rate holding at 4.35% as of August 2026, the cost of servicing debt has become a primary concern for directors across all sectors. Debt consolidation is the professional process of combining multiple liabilities into a single, streamlined facility to optimise liquidity. It’s not just about finding a lower rate; it’s about reclaiming control over your company’s balance sheet.
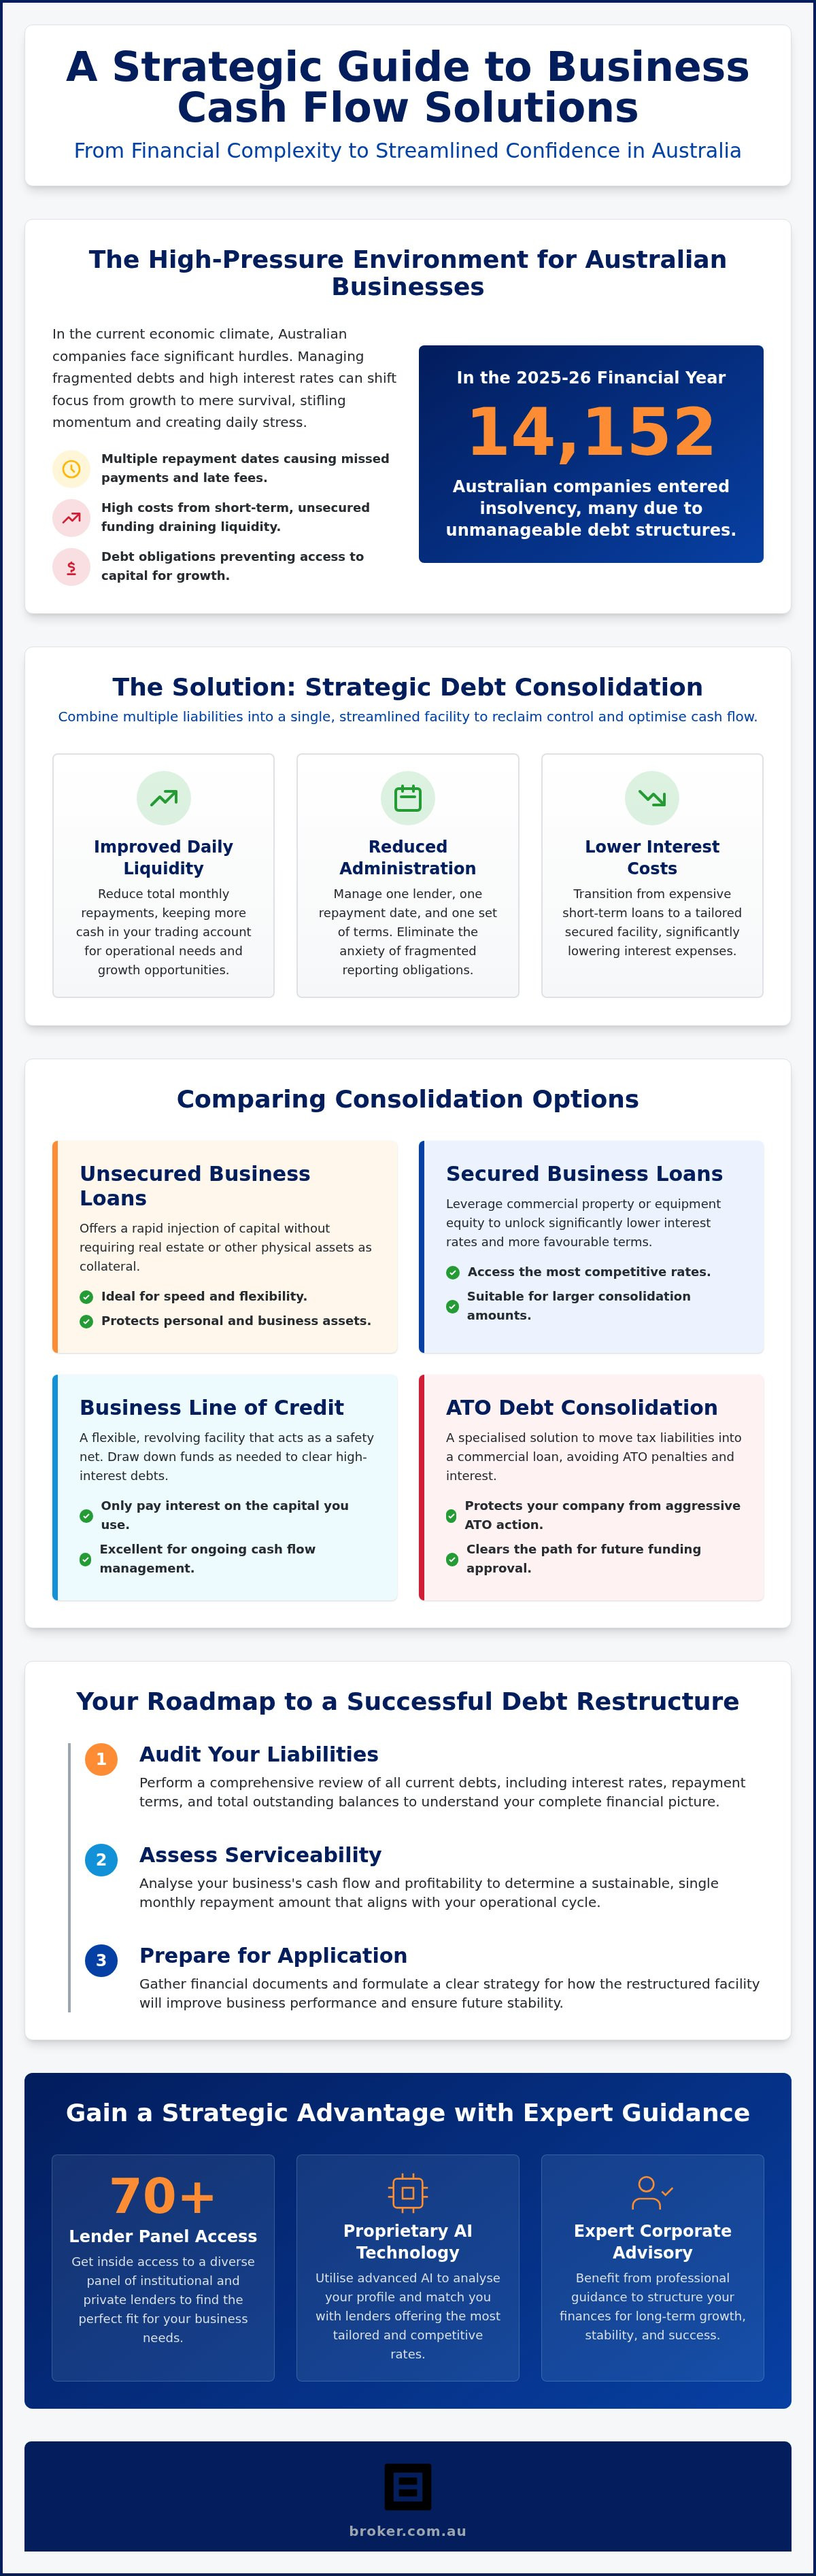
The 2025-26 financial year saw 14,152 Australian companies enter insolvency, with construction and hospitality hardest hit. Many of these failures weren’t caused by a lack of revenue, but by fragmented debt structures that choked daily operations. When your cash flow is drained by five different lenders with five different repayment dates, your focus shifts from growth to survival. This makes 2026 a critical year for a debt audit. A strategic restructure is one of the most effective business cash flow solutions australia has available because it addresses the underlying cause of your financial stress. It aligns your repayments with your actual business cycle, providing a professional foundation for the future.
Choosing a comprehensive restructure over a basic refinance also serves as a tool for improving your credit profile. By closing multiple high-interest facilities and replacing them with a single, well-managed loan, you demonstrate stability. This makes you a more attractive prospect for institutional lenders when you eventually need to scale or sell the business.
The Core Benefits for Australian SMEs
Implementing tailored business cash flow solutions australia wide helps directors move from uncertainty to relief. The primary advantages include:
- Daily Liquidity: Reducing the total monthly repayment amount keeps more cash in your trading account for operational needs.
- Reduced Admin: Dealing with one lender and one set of terms eliminates the anxiety of managing fragmented reporting obligations.
- Lower Interest Costs: Moving from expensive, unsecured short-term funding to a tailored secured facility can significantly lower your interest expenses.
Signs Your Business Needs to Consolidate
Identifying the need for a restructure early ensures you’re in good hands before a pinch becomes a crisis. Watch for these indicators:
- Missed payments or late fees caused by poorly timed repayment dates.
- Using new short-term loans to cover the interest or principal of existing debt.
- A debt-to-income ratio that prevents you from accessing capital for growth or equipment.
If your current obligations are preventing you from pursuing your dreams, your debt structure is working against you. A professional restructure ensures you feel informed and confident about your next steps, moving you toward a state of streamlined confidence.
Effective Business Cash Flow Solutions Australia: Consolidation Options
Selecting the right financial vehicle for your restructure is just as critical as the decision to consolidate. Every business has a unique footprint, and the “best” path depends on your asset position and urgency. For many, Unsecured Business Loans offer a rapid response, providing capital without requiring personal assets as collateral. These are ideal when you need to move quickly to capture a growth opportunity or neutralise a mounting debt. Conversely, Secured Business Loans leverage your commercial property or existing equipment to unlock significantly lower interest rates. By using the equity you’ve already built, you can access the most competitive terms in the 2026 market.
A Line of Credit acts as a flexible safety net, allowing you to draw down funds only when needed to clear high-interest short-term facilities. This revolving structure ensures you aren’t paying interest on capital you aren’t using. For those feeling the pressure of the tax office, ATO Debt Consolidation is a specialised tool. It moves your tax liabilities into a commercial loan structure, protecting your company from the aggressive interest and penalties the ATO applies to late lodgements.
Consolidating ATO Debt and Tax Liabilities
In 2026, the Australian Taxation Office has increased its focus on transparency and debt recovery. Having an outstanding tax balance isn’t just a compliance issue; it’s a major hurdle for your borrowing capacity. Most institutional lenders now require a clean tax portal before approving new growth capital. By wrapping your tax debt into a professional commercial facility, you stop the clock on ATO interest. This strategy allows you to settle your obligations in full immediately, which can improve your credit standing and ensure you’re in good hands for future funding rounds. If you’re feeling overwhelmed by tax obligations, you can discover how a tailored restructure can provide a stress-free path forward.
Refinancing Equipment and Asset Finance
Fragmented asset finance is a common drain on liquidity. You might have multiple chattel mortgages for vehicles or machinery, each with different lenders and varying interest rates. Consolidating these into a single facility simplifies your administration and often reduces your total monthly commitment. This is particularly useful for managing balloon payments. Rather than facing a large, disruptive cash outlay at the end of a term, you can refinance that residual value into your new consolidated loan. Using the equity in your machinery to clear high-interest unsecured debt is one of the most effective business cash flow solutions australia offers to capital-heavy industries like construction or transport. This approach turns your hard assets into a strategic tool for broader financial relief.
Comparing Secured vs. Unsecured Consolidation Strategies
Deciding between a secured or unsecured structure is a pivotal moment for any director. It requires a clear-eyed assessment of your current risk appetite and your long-term vision for the company. While both paths offer professional business cash flow solutions australia wide, the trade-off typically centres on the speed of funding versus the total cost of capital. Secured loans generally offer the most competitive rates, often starting around 7.91% p.a. for variable small business loans. However, they require you to pledge assets like commercial property or machinery. Unsecured options provide the agility needed to stop a cash flow bleed quickly, though they often carry higher interest rates to compensate for the lender’s increased risk.
You must also consider the role of personal guarantees. In the current lending landscape, even “unsecured” facilities often require a director’s guarantee. This means that while no specific asset is tied to the loan, your personal liability remains. Understanding these nuances ensures you’re in good hands when choosing a structure that protects your future borrowing capacity, especially if you plan on pursuing business acquisitions or mergers in the coming years.
Secured Options: Leveraging Property and Assets
Using the equity in your commercial property is often the most efficient way to secure the lowest possible consolidation rates. For directors who need capital beyond what a traditional bank offers, second mortgages and caveat loans provide a viable alternative. A second mortgage sits behind your primary lender, while a caveat loan is a shorter-term, high-speed option that uses a caveat on the property title as security. While using residential equity to fund business operations is common, it introduces a personal layer of risk that requires careful corporate advisory. Our expert guides can help you weigh these pros and cons to ensure your family home remains protected while your business thrives.
Unsecured Options: Speed and Flexibility
When timing is everything, unsecured consolidation is often the fastest way to stabilise your balance sheet. With the private credit market in Australia reaching over A$148 billion in 2026, there are more non-bank options than ever before. These lenders focus on your strong revenue and recent bank statements rather than your asset list. This makes it an ideal choice for service-based businesses or those in a rapid growth phase. Many of our clients use unsecured funding as a bridge, later transitioning to secured debt as the business matures and asset equity grows. This tiered approach provides a seamless path toward lower interest costs without stalling your immediate momentum.
The Roadmap to Consolidating Your Business Debt
Successful debt consolidation starts with a clinical audit of your current liabilities. You need to list every creditor, the specific interest rate you’re paying, and every upcoming repayment date. This transparency allows you to calculate your actual serviceability. You must determine what your business can comfortably repay each month without starving your operations of essential capital. Once you have this baseline, you can begin exploring the most effective business cash flow solutions australia has to offer through a professional lens. List every creditor. Detail every rate. Map out every deadline.
Engaging a specialist broker is the next logical step. A broker provides inside access to niche lenders and private credit providers who don’t deal directly with the public. These institutions often have a higher appetite for complex restructures than traditional banks. By leveraging proprietary AI technology, we can match your specific profile with the right lender instantly, ensuring you’re in good hands from the first consultation. The final stage is the execution, where old high-interest debts are cleared and your new, structured repayment cycle begins.
Documentation and Financial Modelling
In 2026, lenders are scrutinising BAS and financial statements with increased rigour. You need to ensure your lodgements are up to date to avoid immediate rejection. Beyond the raw numbers, you must be able to articulate your company’s turnaround story. This narrative explains why you’re consolidating and how the new structure will facilitate growth. We use proprietary AI-driven financial modelling to predict your post-consolidation cash flow. This gives both you and the lender confidence that the new facility is sustainable and tailored to your long-term dreams.
Navigating Lender Requirements
Australian lenders today are looking for stability and a clear path to repayment. If you have credit impairments or historical black marks, don’t assume consolidation is off the table. Non-bank lenders often prioritise your current revenue and future potential over past hiccups. They want to see that your business model is sound and that a restructure will genuinely solve your liquidity issues. The difference between a major bank and a non-bank lender in the current market is often the level of personal attention and flexibility they can offer to situations that fall outside of the norm. If you’re ready to move from complexity to streamlined confidence, you can get started with a professional assessment here.
Why a Strategic Broker is Your Best Asset for Cash Flow
Choosing a strategic broker in 2026 is about more than just finding a loan; it’s about securing a high-level fixer for your company’s future. While traditional banks have become more stringent with their serviceability requirements, we provide inside access to the best rates across a panel of over 70 lenders. Our proprietary AI technology scans the market instantly to find the perfect match for your specific profile. This data-driven approach identifies niche business cash flow solutions australia wide that are often hidden from the general public. It ensures you aren’t wasting time on applications that don’t align with current lender appetites.
The value of professional corporate advisory cannot be overstated. If you’re planning a business acquisition or preparing for a future sale, your debt structure must be impeccable. We use sophisticated financial modelling to ensure your liabilities support your long-term dreams rather than hindering your growth. This strategic oversight turns your debt into a tool for expansion, providing you with the liquidity needed to move quickly when opportunities arise. You gain the advantage of wholesale rates and tailored terms that direct-to-bank applicants simply cannot access.
The Broker.com.au Advantage
Our award-winning team, including specialists like Matt, Kylie, and Flavio, organises complex restructures with a level of personal attention that large-scale banks lack. We specialise in finding professional solutions for situations that fall outside of the norm. Whether you’re managing intricate SMSF loans or need to consolidate high-interest equipment finance, our human-led advisory ensures you’re in good hands. We manage the entire process from initial application to final funding, making the experience entirely stress-free for you and your management team. This boutique level of service ensures your file is never just another number in a system.
Getting Started with Your Restructure
We believe the journey toward financial relief should start with a low-pressure conversation. Our “I’m interested” approach is designed to respect your time and your goals without the anxiety of a hard sell. We provide a clear, logical path that leads you away from financial complexity and toward a state of streamlined confidence. Our team is proactive and ready to go above and beyond to ensure your business has the working capital it needs to thrive in the current economy. If you’re ready to reclaim your cash flow and lower your total cost of capital, we’re here to guide you.
I’m interested in consolidating my business debt
Reclaim Your Financial Momentum and Scale with Confidence
Strategic debt consolidation is more than a simple refinance; it’s a professional pivot that aligns your liabilities with your actual business cycle. By auditing your current obligations and choosing the right structure, you can clear pressing ATO debt and reduce the administrative burden of fragmented repayments. Implementing professional business cash flow solutions australia wide allows you to move from daily survival to sustainable, long-term growth.
As an award-winning Australian brokerage, we use proprietary AI matching technology and expert corporate advisory to ensure your restructure is seamless. You don’t have to manage these high-stakes decisions alone. We’re here to provide the inside access and local insights needed to secure the best possible rates for your unique situation. Our team is ready to help you move from financial complexity toward a state of streamlined confidence.
I’m interested in exploring my consolidation options
Your business dreams are within reach when your debt structure works for you rather than against you. Let’s start the conversation today and put your company on a professional path to success.
Frequently Asked Questions
Can I consolidate ATO debt with a business loan in Australia?
Yes, you can consolidate ATO debt into a professional commercial facility. This is one of the most proactive business cash flow solutions australia offers to avoid the escalating interest and penalties applied by the tax office. By clearing your tax portal immediately, you improve your standing with other lenders. This strategy moves you from a state of uncertainty toward streamlined confidence, ensuring your business remains compliant while preserving your daily trading capital.
Will business debt consolidation hurt my credit score?
Applying for a new loan involves a credit enquiry, which might cause a temporary minor dip in your score. However, the long-term impact is often positive. By closing multiple high-interest facilities and replacing them with a single, well-managed repayment, you demonstrate improved financial stability. This professional restructure shows institutional lenders that you’re in good hands and can manage debt responsibly, making you a more attractive prospect for future growth capital.
What is the difference between refinancing and debt consolidation?
Refinancing typically involves replacing a single existing loan with a new one to secure better terms or a lower rate. Debt consolidation is a more comprehensive strategy where you merge multiple fragmented liabilities into one streamlined facility. This approach is designed to simplify your administration and reduce your total monthly commitment. It’s a high-level fix that transforms your balance sheet from a complex web of dates into a single, manageable repayment cycle.
Do I need to provide property as security for a consolidation loan?
No, property security isn’t always mandatory. You can choose an unsecured business loan, which relies on your revenue and bank statements rather than physical assets. While these facilities offer speed and flexibility, secured options using commercial property or equipment typically provide lower interest rates. We act as an expert guide to help you weigh these choices based on your current risk appetite and the specific needs of your business restructure.
How much can I save by consolidating my business debts?
Your savings depend on the gap between your current rates and the new consolidated facility. For example, moving from high-cost unsecured funding to a secured loan at rates closer to 7.91% p.a. can significantly reduce your interest costs. Beyond the dollar savings, you reduce the hidden costs of late fees and administrative stress. Our proprietary AI technology identifies the most efficient path to lower your total cost of capital across a panel of over 70 lenders.
Can I consolidate my debts if I have a “low doc” business?
Yes, “low doc” businesses can definitely access consolidation options. If your financial statements aren’t fully up to date, we can leverage your bank statements and BAS to demonstrate serviceability. Many non-bank lenders in the Australian market specialise in these situations that fall outside of the norm. This ensures you still have access to the best rates without the rigid documentation requirements often imposed by the major banks in 2026.
What documents do I need to apply for business debt consolidation?
To start your professional restructure, you’ll generally need your most recent Business Activity Statements (BAS), six months of bank feeds, and a clear list of your current liabilities. For more complex or secured loans, we might also require your latest financial statements and director identification. Having these organised ensures a seamless application process. Our team manages the complexity for you, making the transition from fragmented debt to a single facility entirely stress-free.
How long does the consolidation process typically take?
The timeframe varies based on the complexity of your restructure. Unsecured business cash flow solutions australia wide can often be approved within 24 to 48 hours using our proprietary AI matching technology. More complex secured loans or corporate advisory restructures typically take between two and four weeks to finalise. We work proactively to ensure you’re informed at every stage, providing a clear path from your initial enquiry to the final settlement.
