
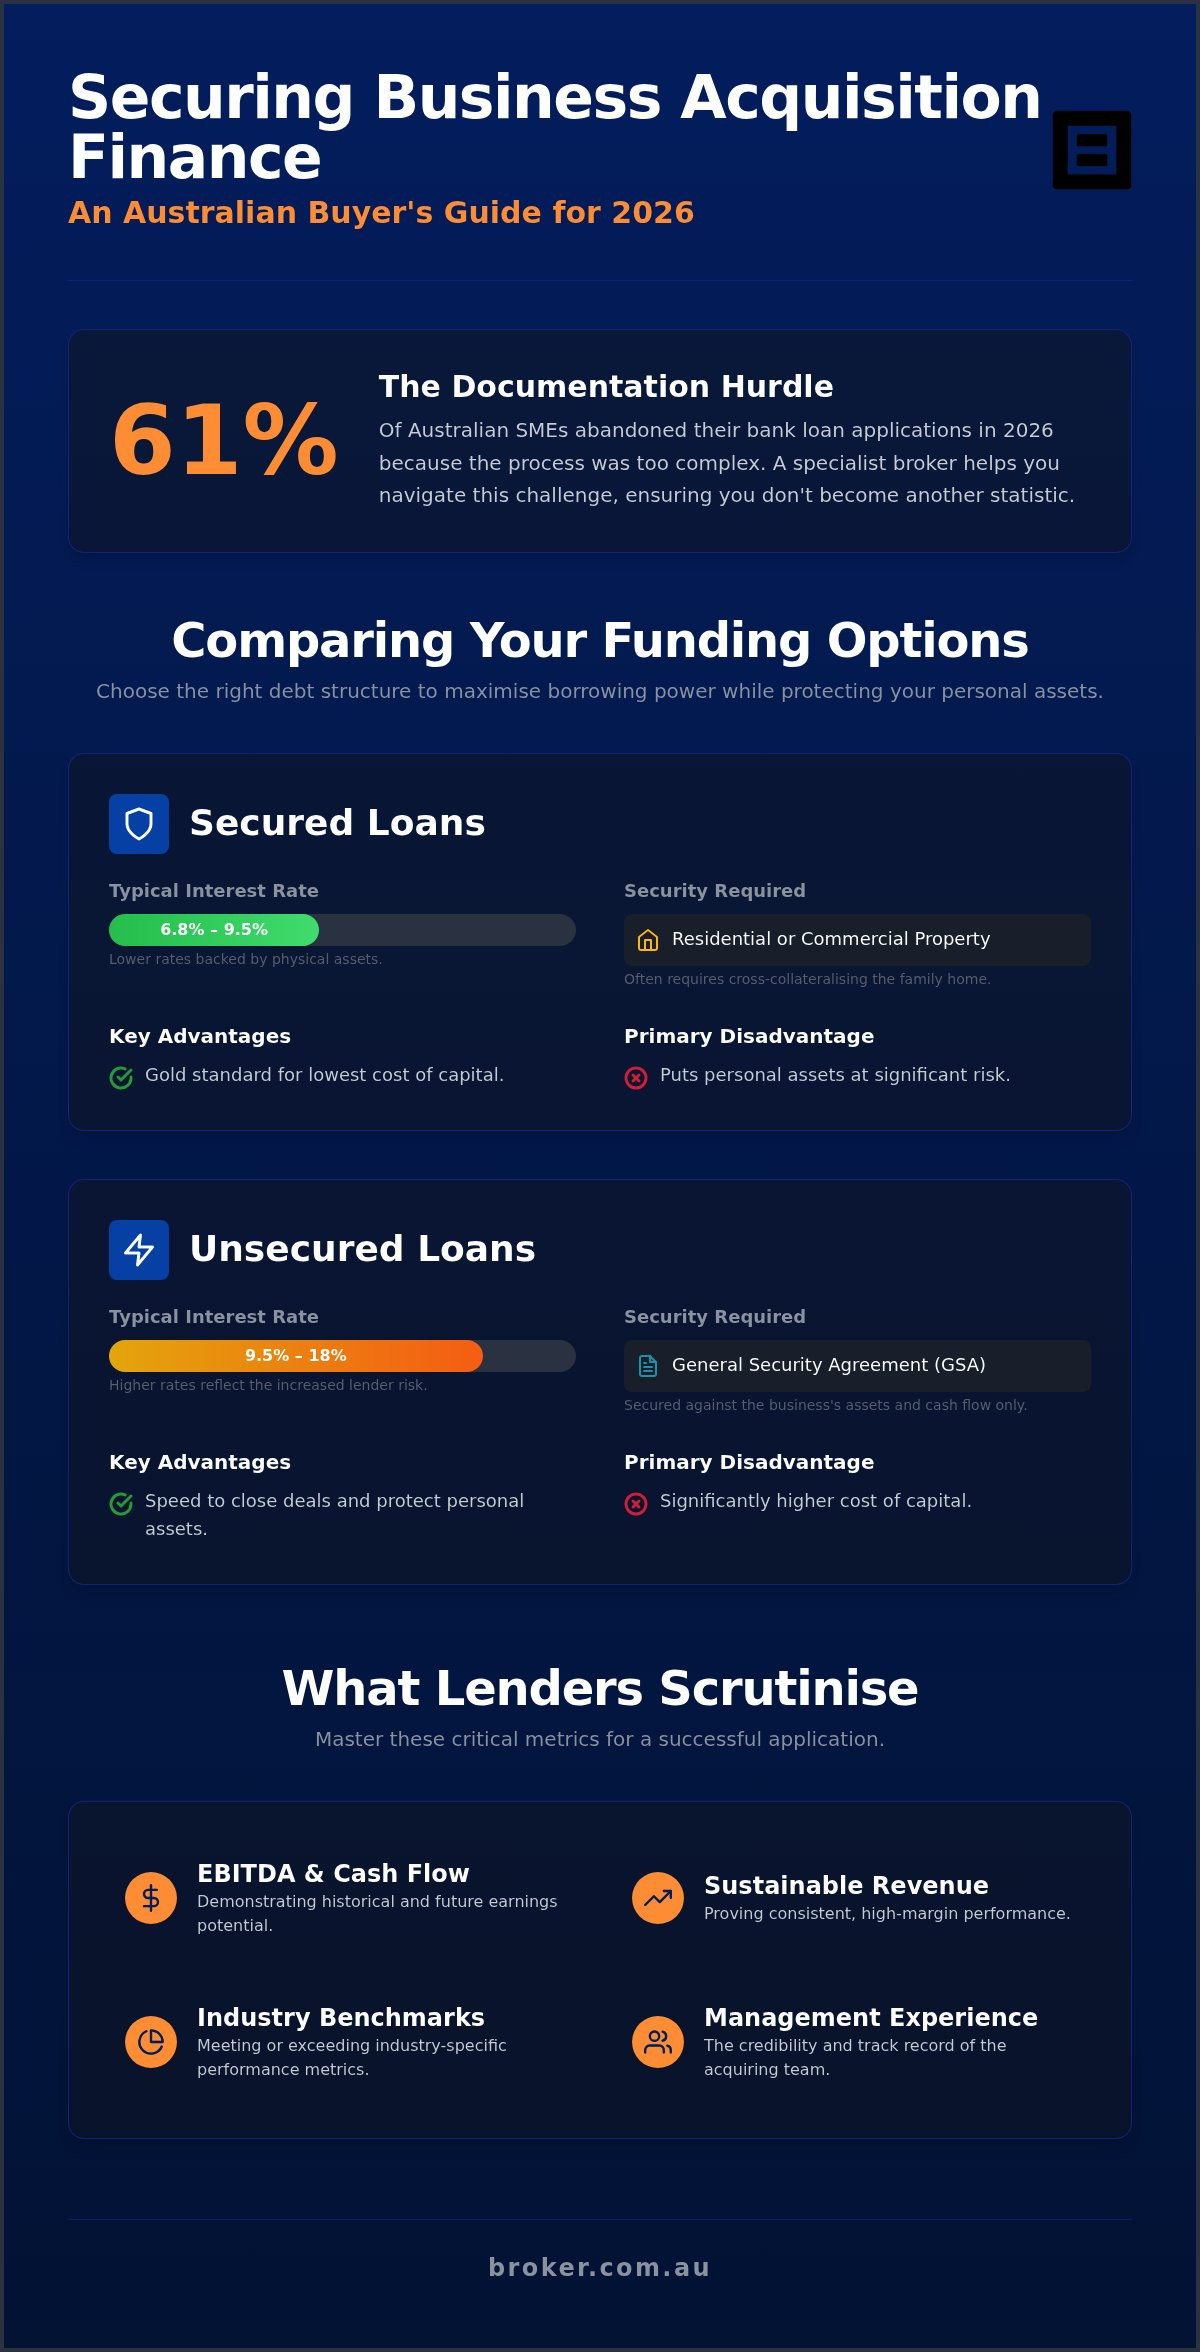
Did you know that 61% of Australian SMEs abandoned their bank loan applications in 2026 simply because the documentation hurdles became insurmountable? When you’re trying to secure a strategic acquisition, the last thing you need is a rigid bank manager rejecting your deal because of high goodwill value or demanding your family home as collateral. Partnering with a specialist business acquisition loan broker australia wide ensures you don’t become another statistic while trying to scale your operations.
It’s natural to feel uneasy about complex financial modelling or the threat of cross-collateralising your personal assets to fund a new venture. You deserve a debt structure that leverages the target business’s cash flow and settles quickly enough to keep the vendor happy. This guide reveals the exact steps to secure funding in the current market, from navigating APRA’s latest debt-to-income limits to accessing a panel of over 50 lenders. You’ll learn how to gain inside access to competitive rates and bespoke structures that keep your acquisition on track without risking everything you’ve already built.
Key Takeaways
- Learn why the 2026 Australian lending market increasingly favours alternative and AI-driven finance over traditional bank routes for strategic acquisitions.
- Discover how to select between secured and unsecured funding to maximise your borrowing power while keeping your personal assets protected.
- Master the critical financial metrics, including EBITDA and industry-specific benchmarks, that lenders scrutinise during your business purchase application.
- Understand how a dedicated business acquisition loan broker australia provides the inside access needed to unlock tailored debt structures from a panel of over 50 lenders.
- See how proprietary AI technology can match your unique scenario with best in class lenders to ensure a seamless and efficient settlement process.
Table of Contents
- Understanding Business Acquisition Finance in the Australian Market
- Comparing Your Funding Options: Secured, Unsecured, and Asset Finance
- What Australian Lenders Look for in a Business Purchase
- A Step-by-Step Guide to Securing Your Business Loan
- Navigating the Lending Landscape with an Expert Broker
Understanding Business Acquisition Finance in the Australian Market
Acquiring a company involves more than just signing a contract; it requires a sophisticated debt structure that aligns with the target’s cash flow. Unlike standard commercial lending, which often focuses on physical assets like machinery or property, acquisition finance evaluates the future earnings potential of the entity you’re buying. With the Reserve Bank of Australia (RBA) maintaining a cash rate of 4.35% as of May 2026, the cost of capital is a critical variable in your financial modelling. You need a structure that remains sustainable even if market conditions fluctuate.
Buying an established business is generally more straightforward to fund than launching a start-up from scratch. Lenders value the certainty of historical EBITDA and existing customer loyalty. Despite this, the 2026 landscape has shifted significantly. While major banks remain conservative, alternative and AI-driven finance providers are filling the gap left by traditional institutions. Engaging a specialist business acquisition loan broker australia gives you a distinct edge. We use proprietary tools to match your specific scenario with lenders who understand your industry, moving you beyond the 61% of applicants who give up due to documentation hurdles.
The “Goodwill Gap”: Why Traditional Banks Often Say No
Traditional lenders often struggle with the concept of “goodwill.” This represents the intangible value of a brand, its reputation, and its client relationships. Because you can’t seize goodwill like a piece of real estate, banks frequently impose strict serviceability requirements or demand the family home as security. This friction is why many deals fall through at the eleventh hour. Modern cash-flow lending ignores these rigid hurdles, focusing instead on high-margin performance and sustainable revenue. By looking at the business’s ability to service debt through its own operations, we can often secure funding that traditional banks would reject.
The Strategic Advantage of Acquisition Debt
Strategic debt isn’t just about covering a purchase price; it’s about protecting your liquidity. By employing a Leveraged Buyout (LBO) model, you can acquire a high-performing competitor while keeping your own working capital intact for post-settlement growth. This approach offers clear tax benefits, as the interest paid on loans used for business acquisition is generally tax-deductible. A tailored structure also ensures that your personal wealth remains separate from business liabilities. You don’t need to put your family home on the line to expand your footprint. Our experts provide inside access to debt structures that insulate your personal assets while providing the competitive rates required for a successful takeover.
Comparing Your Funding Options: Secured, Unsecured, and Asset Finance
Securing the right capital isn’t a one-size-fits-all exercise. In 2026, savvy buyers use a mix of products to fund their vision. Whether you’re leveraging residential equity for a secured loan or prioritising speed with an unsecured facility, your choice dictates your post-settlement breathing room. A professional business acquisition loan broker australia will often suggest a hybrid approach, layering different finance types to satisfy both the vendor’s price and your operational needs. This strategy ensures you don’t over-leverage a single asset class while keeping your cost of capital as low as possible.
The 2026 lending market has become increasingly borrower-friendly for those who know where to look. While major bank rates for secured loans sit between 6.8% and 9.5%, non-bank lenders are providing aggressive competition with flexible terms. For many, the goal is a seamless transition that doesn’t put personal assets at unnecessary risk. You can find detailed guidance on the regulatory standards for these products via Australian government business finance resources. Understanding these options allows you to enter negotiations with a position of strength and a clear funding roadmap.
Secured vs Unsecured: Which Suits Your Deal?
Secured loans remain the gold standard for low-interest funding, provided you have the equity to back them. However, the risk of cross-collateralising your family home is a significant deterrent for many entrepreneurs. Unsecured business loans, despite rates ranging from 9.5% up to 18%, offer the speed required to close deals before competitors can react. Most lenders will require a General Security Agreement (GSA) over the business assets regardless of the loan type. This gives them a registered interest in the company’s accounts and equipment without necessarily touching your personal real estate portfolio.
Specialised Finance for Equipment and Fit-outs
Don’t overlook the internal value of the target business. Asset finance allows you to use the company’s existing fleet, heavy machinery, or medical equipment as collateral. This is particularly effective for hospitality or retail acquisitions where a post-purchase refresh is needed. By using fit-out finance for renovations, you preserve your main acquisition loan for the actual purchase price. Carving out vehicle or equipment finance as separate sub-facilities often leads to better overall terms. If you want to see how these layers can work for your specific purchase, you might want to explore our tailored finance solutions to find a structure that fits.
What Australian Lenders Look for in a Business Purchase
Lenders in 2026 have moved beyond the traditional “rear-vision mirror” approach to credit. While historical tax returns still matter, modern approval processes focus on the future sustainability of the entity under your management. Engaging a business acquisition loan broker australia ensures your application is framed through the lens of “Capacity, Collateral, and Character”—the three pillars of lending. Capacity proves you can service the debt; collateral provides a safety net; and character, often demonstrated through your industry track record, gives the lender confidence in your leadership.
The speed of approval has also transformed. 2026 AI assessments now allow lenders to verify real-time cash flow data via secure bank feeds, significantly accelerating verification times compared to traditional manual reviews. This technology allows “best in class” lenders to look past static balance sheets and reward businesses with high-velocity, consistent revenue streams. By presenting a professional Business Plan that highlights your relevant industry experience, you transform a risky “outside the norm” scenario into an attractive investment for a lender.
The Crucial Role of Financial Modelling
EBITDA is defined as a company’s net earnings before interest, taxes, depreciation, and amortisation are subtracted. This is the primary metric Australian lenders use to determine your borrowing power. However, your debt-to-income (DTI) ratio is now equally vital. Effective February 1, 2026, APRA has restricted high-DTI loans exceeding six times the borrower’s income, meaning your pro-forma financials must be airtight. These projections should clearly show how the business will perform post-acquisition, accounting for planned efficiencies and growth. You should also consult the ASIC small business guidance to ensure your corporate structure meets current compliance standards before submitting these models.
Valuing and Funding Goodwill Strategically
Goodwill remains the most significant hurdle in Australian acquisitions, often making up the bulk of the purchase price in service-based industries. To bridge the gap between tangible assets and the sale price, you must look beyond the major banks. Negotiating vendor finance, where the seller leaves a portion of the purchase price in the business as a secondary loan, is a powerful way to reduce the initial debt burden. A specialist broker identifies niche lenders who are comfortable with high-goodwill sectors, ensuring you don’t stall because a traditional bank won’t look past the lack of physical security. This tailored approach allows you to secure the full amount required while keeping your personal assets insulated from the deal.
A Step-by-Step Guide to Securing Your Business Loan
Securing a loan for a strategic acquisition isn’t a linear path; it’s a sequence of calculated moves designed to build lender confidence. While some digital lenders promise a 24-hour approval for small working capital needs, a complex acquisition requires a more rigorous approach to ensure the debt structure doesn’t cripple your new venture. Following a structured roadmap allows you to maintain momentum and satisfy the vendor’s timeline while protecting your personal interests.
- Step 1: Preliminary Assessment. Before looking at a specific target, you must determine your true borrowing power. This involves a deep dive into your current assets, liabilities, and the specific industries lenders are currently favouring.
- Step 2: Engaging an Expert Broker. A specialist business acquisition loan broker australia provides the “inside access” needed to reach niche lenders and secure rates not available to the general public. We manage the heavy lifting, allowing you to focus on due diligence.
- Step 3: Compiling the Information Memorandum. This is your pitch to the bank. It combines the target business’s financials with your vision for growth, proving the acquisition is a viable, low-risk investment.
- Step 4: Term Sheet Comparison. Once submissions are made, you’ll receive various offers. We help you compare more than just the interest rate, looking at the fine print that impacts long-term flexibility.
- Step 5: Settlement and Handover. After legal reviews and final approvals, funds are disbursed. This stage requires precise coordination between your solicitors, the vendor, and the lender to ensure a seamless transition of ownership.
If you’re ready to see how these steps apply to your specific situation, you can start your preliminary assessment today with our expert team.
The Documentation Checklist: Being “Lender Ready”
Lenders in 2026 are meticulous about documentation. You’ll need to provide Section 52 statements or equivalent profit and loss data for at least the last two financial years. Directors must also submit detailed Personal Financial Position (PFP) statements. It’s vital to address any historical credit issues early; a clean file is often the difference between a standard bank rate and a high-interest alternative. Having these items organised before you engage a lender signals that you are a sophisticated and low-risk borrower.
Negotiating Terms Beyond the Interest Rate
The headline interest rate is only one part of the equation. You must also negotiate loan covenants, which are the financial rules you must live by post-settlement, such as maintaining a specific debt-service cover ratio. Balancing your monthly cash flow might involve choosing between a balloon payment at the end of the term or standard principal and interest repayments. For many acquisitions, securing an “Interest Only” period for the first six months is a game-changer. This preserves cash while you’re finding your feet and implementing operational changes in the new business.
Navigating the Lending Landscape with an Expert Broker
Finding the right capital for a strategic purchase shouldn’t feel like a second full-time job. A professional business acquisition loan broker australia provides a single point of entry to a panel of over 50 lenders, ranging from the big four banks to private credit providers. This streamlined approach replaces the frustration of multiple applications with a single, professional submission. By leveraging our proprietary AI matching technology, we identify “best in class” lenders who actually have an appetite for your specific industry and deal size. This ensures you don’t waste time with institutions that are currently avoiding your sector.
This “inside access” is about more than just convenience; it’s about the long-term cost of your debt. Securing a rate even half a percent lower than the market average can save you thousands of dollars over the life of the loan. We manage the intense back-and-forth with bank credit departments, acting as your seasoned partner to resolve technical queries before they become deal-breakers. You stay focused on the operations of the target business while we ensure the funding remains on track. It’s a stress-free path that moves you from a state of uncertainty toward a feeling of streamlined confidence.
From Complexity to Confidence: The Broker.com.au Process
We project the personality of an expert guide who is deeply knowledgeable about the complexities of the Australian lending landscape. Our team thrives on “outside the norm” scenarios, such as acquisitions involving complex SMSF structures or high-goodwill values that traditional banks typically reject. We operate on a low-pressure, “I’m interested” philosophy. This conversation-first approach allows you to explore options without the aggressive sales tactics common in the finance industry. Whether you’re working with Flavio, Matt, or Kylie, you’ll receive boutique-level attention that prioritises your long-term success and specific business dream.
Beyond the Loan: Corporate Advisory and Ongoing Support
Strategic growth requires more than a one-off transaction. We provide ongoing support by restructuring existing debt to improve your acquisition capacity and reviewing your facilities as the market evolves. If the RBA cash rate moves or new lenders enter the market, we proactively check if your current structure is still the most efficient option. This commitment ensures you always have a high-level fixer in your corner to manage your financial needs. If you’re planning your next move, I’m interested in business acquisition funding and would like to discover how a tailored structure can protect my personal assets while providing the capital I need to grow.
Secure Your Future with a Tailored Acquisition Strategy
The 2026 Australian lending landscape offers unprecedented opportunities for those who look beyond traditional bank hurdles. Success hinges on engineering a debt structure that protects your personal assets while leveraging the target business’s cash flow. By understanding the nuances of EBITDA and the “goodwill gap”, you can navigate the path from preliminary assessment to final settlement with streamlined confidence. It’s about moving from a state of uncertainty to a position of strategic strength.
Partnering with an award-winning business acquisition loan broker australia ensures you aren’t limited by a single bank’s rigid criteria. We provide inside access to a panel of over 50 lenders, using proprietary AI technology to match your specific needs with the most competitive rates and flexible terms. Whether you’re handling an “outside the norm” scenario or a straightforward purchase, our expert guides are here to make the process efficient and stress-free. We handle the technical complexities so you can focus on leading your new venture.
If you’re ready to turn your business dream into a reality, I’m interested in exploring my business loan options. Your next strategic growth milestone is well within reach when you have the right specialists in your corner.
Frequently Asked Questions
Can I get a business loan with no deposit in Australia?
You can often secure funding without a cash deposit if you have sufficient equity in other assets, such as commercial property or a residential home. Most lenders look for 20% to 30% security or “skin in the game” to mitigate their risk. You might also use vendor finance to bridge the gap between your available capital and the purchase price. A specialist business acquisition loan broker australia can help you structure a deal that minimises your upfront cash requirement.
How long does it take to secure a loan to buy an existing business?
Settlement timelines typically range from two to six weeks depending on the complexity of the deal and the quality of your documentation. While simple unsecured business loans can sometimes be approved in 24 to 48 hours, a full strategic acquisition involves legal reviews and valuation reports. Using proprietary AI technology, we accelerate the matching process to ensure you meet the vendor’s settlement deadline without the stress of typical bank delays or administrative hurdles.
What is the average interest rate for a business acquisition loan in 2026?
As of mid-2026, interest rates vary based on your security and the lender’s risk profile. With the RBA cash rate at 4.35%, secured business loans from major banks generally range between 6.8% and 9.5% p.a. Unsecured options typically sit between 9.5% and 18% p.a. because of the higher risk to the lender. We provide inside access to rates from over 50 lenders, ensuring you don’t pay an unnecessary premium for your acquisition debt.
Do I have to use my family home as security for a business loan?
You don’t have to put your family home at risk to fund a business purchase. While banks often prefer real estate security for lower rates, we specialise in structures that use the target business’s assets or cash flow as collateral. Options include a General Security Agreement (GSA) over the company or using specialised asset finance for equipment. This approach protects your personal wealth while providing the necessary capital for your strategic acquisition.
What is vendor finance and should I use it for my acquisition?
Vendor finance occurs when the seller agrees to receive a portion of the purchase price over time rather than as a lump sum at settlement. It’s an excellent tool for bridging the “goodwill gap” that traditional banks often hesitate to fund. Using this method signals the seller’s confidence in the business’s future performance. It can also reduce the total amount you need to borrow from a lender, improving your debt-serviceability ratios and overall borrowing power.
Can I buy a business using an unsecured business loan?
Yes, you can use an unsecured business loan for an acquisition if the target business demonstrates exceptionally strong and consistent cash flow. These loans don’t require specific physical collateral like property, making them ideal for service-based industries with high goodwill. While the interest rates are higher than secured options, the speed and flexibility they offer can be the difference between winning a competitive deal and missing out entirely on a strategic growth opportunity.
What documents are required for a business loan application in Australia?
Lenders require a comprehensive documentation pack to assess your application. You’ll typically need two years of historical tax returns and profit and loss statements for the target business, along with a Section 52 statement if required. Directors must provide Personal Financial Position (PFP) statements and a robust Business Plan. We help you compile an Information Memorandum that addresses lender concerns regarding EBITDA and debt-to-income ratios before the application reaches the credit department.
How does a business loan broker differ from a local bank manager?
A local bank manager can only offer products from their own institution, regardless of whether they fit your specific needs. In contrast, a business acquisition loan broker australia provides access to a panel of over 50 lenders, including private credit and non-banks. We use proprietary AI to match you with the best in class solution for your specific “outside the norm” scenario. Our focus is on your strategic dream, not just meeting a bank’s internal targets.
