
With nearly 20% of Australian franchisees now controlling over half of all locations, the scale of competition for prime sites and capital has never been higher. It’s natural to feel overwhelmed by the latest Franchising Code of Conduct updates or the fear that a major bank might reject your application because they don’t understand your specific brand’s value. That’s where a specialist franchise finance broker in Australia, like Broker.com.au, ensures you aren’t just another number in a lender’s queue. You deserve to feel like you’re in good hands while pursuing your business goals.
You likely want a clear path to settlement without the stress of wondering if your security is enough or if the interest rates are truly competitive. This guide will help you master the complexities of franchise lending so you can secure the capital needed to launch or expand your business with confidence. We’ll preview which lenders currently favour your specific brand, explain the nuances between secured and unsecured options, and show you how to streamline your application for a faster, more efficient approval process.
Key Takeaways
- Understand why Australian lenders view established franchise systems as lower risk than independent start-ups, potentially unlocking more favourable lending terms.
- Learn how to strategically balance secured and unsecured business loans to protect your personal assets while maintaining healthy cash flow.
- Master the “Five Cs” of credit and identify the critical documents required to streamline your application and avoid common lender rejections.
- Discover how a specialist franchise finance broker australia provides inside access to competitive rates and tailored solutions that major banks often overlook.
- Gain a clear, stress-free roadmap from your initial borrowing capacity assessment to final settlement, ensuring your business launch stays on track.
Table of Contents
- Understanding the Franchise Lending Landscape in Australia
- Types of Funding to Buy a Franchise: Secured vs Unsecured
- What Lenders Actually Look for in a Franchise Application
- Step-by-Step Guide to Organising Your Franchise Finance
- Why Partnering with a Specialist Broker is Your Best Move
Understanding the Franchise Lending Landscape in Australia
Entering the world of business ownership is a high-stakes decision that requires more than just a good idea. In the Australian market, franchise finance is treated as a specialised category of business acquisition funding rather than a standard commercial loan. Because Franchising in Australia is governed by a strict Code of Conduct, lenders see a level of transparency and structural security that simply isn’t present with independent ventures. A specialist franchise finance broker australia helps you leverage this transparency to move from a state of uncertainty toward a feeling of streamlined confidence.
Major Australian banks often maintain “Accredited Franchise Lists” to manage their risk. If your chosen brand appears on one of these lists, the bank has already vetted the system’s management, profitability, and historical success. This pre-approval of the brand itself can fast-track your personal application and may allow you to borrow a higher percentage of the purchase price. However, the Franchise Agreement remains the primary document in this process. It serves as the legal backbone of your application, detailing the term of your tenure and the support you’ll receive, which provides lenders with the certainty they need to approve your capital.
Why Lenders Prefer Franchises Over Independent Start-ups
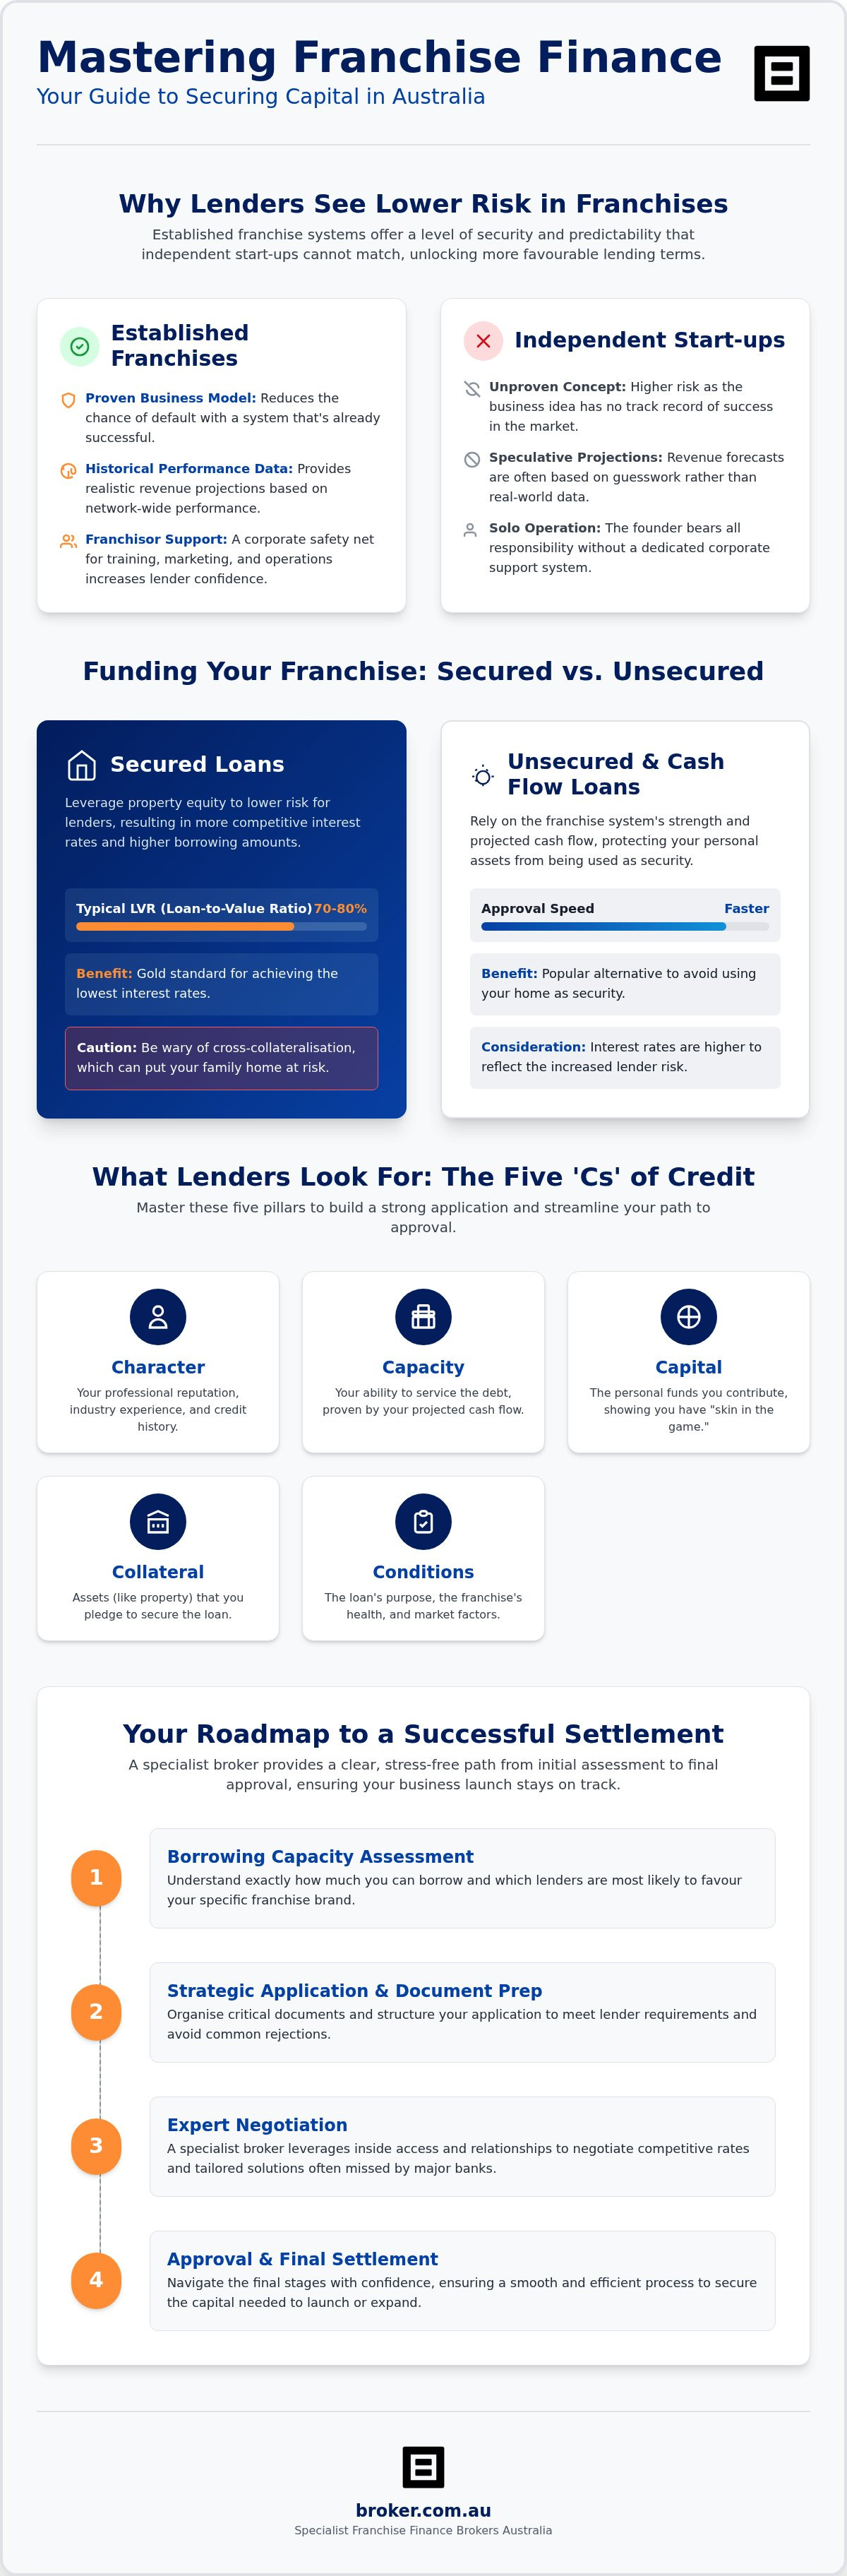
Lenders are risk-averse by nature. They prefer franchises because they offer a proven business model that significantly reduces the chance of default. Unlike a start-up where you’re often guessing at potential revenue, a franchise provides historical data from other locations within the network. This data provides a realistic benchmark for your performance projections. Furthermore, the franchisor’s support acts as a safety net. Having a corporate team dedicated to your training and marketing increases lender confidence that the business will remain viable through various market cycles.
The 2026 Outlook for Australian Franchise Finance
The current financial climate in 2026 has made debt serviceability the most critical factor for new acquisitions. While interest rate trends continue to influence borrowing power, we’ve seen a significant emergence of non-bank lenders. these firms often offer more flexible terms and faster approval times than traditional banks, which can be a game-changer if you’re trying to meet a tight settlement deadline. The Franchise Tier system is a classification used by credit departments to rank brands from Tier 1 to Tier 3 based on their proven track record, network stability, and overall risk to the lender. Working with an expert guide ensures you understand where your brand sits and which lenders are currently hungry for that specific type of risk.
Types of Funding to Buy a Franchise: Secured vs Unsecured
Choosing the right capital structure is a strategic exercise that goes beyond simply finding the lowest interest rate. To launch successfully, you’ll likely need a combination of products tailored to your specific franchise model. A specialist franchise finance broker australia acts as a high-level fixer, helping you layer different types of debt to preserve your personal liquidity. This ensures you aren’t just getting a loan, but building a sustainable financial foundation for your new venture.
Secured Loans: Leveraging Property for Lower Rates
Secured business loans remain the gold standard for achieving the most competitive interest rates. By leveraging the equity in your residential or commercial property, you provide the lender with tangible security, which significantly lowers their risk profile. In the Australian market, typical Loan-to-Value Ratios (LVR) for franchise acquisitions usually hover around 70% to 80% when backed by property. While this provides a clear path to approval, you must be wary of cross-collateralisation. This occurs when a lender ties your family home directly to your business debt. If the business faces headwinds, your primary residence could be at risk. It’s a complex area where professional guidance ensures you remain in good hands throughout the life of the loan.
Unsecured and Cash-Flow Lending
If you’d prefer not to use your home as security, unsecured business loans are an increasingly popular alternative. These facilities rely on the projected cash flow and the established track record of the franchise system rather than your physical assets. While interest rates are naturally higher to reflect the lender’s increased risk, the speed of approval is a major benefit. The rise of fintech lenders in 2026 has made it possible to secure unsecured capital in days rather than weeks. This is particularly useful for fast-moving opportunities where delaying the settlement could mean losing a prime territory to a competitor.
A comprehensive funding package often requires more than a single loan. For many retail or hospitality franchises, fit-out finance is a critical tool to cover the high costs of interior construction and branding. You might also utilise asset finance to spread the cost of essential machinery, technology, or vehicles over several years. Don’t forget to account for working capital finance to cover the initial “burn period” before the business reaches its break-even point. If you’re feeling overwhelmed by these options, let us know you’re interested in a tailored strategy. All funding arrangements must align with the disclosure requirements set out in the Franchising Code of Conduct, ensuring you have a transparent view of your obligations before signing on the dotted line.
What Lenders Actually Look for in a Franchise Application
Lenders in the Australian market don’t just assess your personal creditworthiness; they evaluate the entire ecosystem of the brand you’re joining. Specialist knowledge from a franchise finance broker australia ensures your application speaks the language of a credit officer who is applying the “Five Cs” (Character, Capacity, Capital, Collateral, and Conditions) through a very specific franchising filter. Moving from uncertainty to a state of streamlined confidence requires understanding that the bank is effectively “partnering” with both you and the franchisor.
The Strength of the Franchise System
Banks prioritise brands with a robust financial pulse and a proven track record on Australian soil. They look at how many years the system has been operating and, more importantly, the historical success rate of its franchisees. A high failure rate within a network is a significant red flag that can lead to an immediate rejection, regardless of your personal strength. Being listed on a “Preferred Lender” list for major banks acts as a powerful endorsement; it suggests the bank has already vetted the system’s unit economics, often resulting in faster approvals and more competitive interest rates. For newer or unaccredited systems, the path to funding is more complex, requiring a “High-Level Fixer” to present the brand’s growth trajectory and management expertise as a compelling case for risk mitigation.
Your Personal Profile as a Franchisee
Professional experience remains a cornerstone of the lender’s assessment. Even in a turn-key system with comprehensive training, banks value industry-specific experience because it reduces the operational risk during the critical first twelve months. If you’re transitioning from a different sector, you must demonstrate how your transferable management skills will ensure the business’s success. Maintaining a clean credit history and providing a transparent statement of your personal assets and liabilities is essential to show you have the financial resilience to handle setbacks. A professional, data-backed Business Plan is a non-negotiable requirement for securing high-level approval and proving you have the “skin in the game” necessary to succeed.
Physical location and lease terms are the final pieces of the risk puzzle. Lenders generally require your lease term to meet or exceed the duration of the loan. If you’re seeking a seven-year loan but only have a five-year lease with no guaranteed options to renew, the bank will likely view the deal as too risky. They need to know the business has the legal right to trade for the entire time you’re scheduled to be repaying the debt. By addressing these factors early, you ensure the application process remains stress-free and your business goals stay within reach.
Step-by-Step Guide to Organising Your Franchise Finance
Securing capital for a new venture is a journey that requires absolute precision. A specialist franchise finance broker australia acts as your expert guide, moving you from the complexity of lender requirements toward a feeling of streamlined confidence. It begins with an initial consultation to determine your borrowing capacity and identify which lenders in our vast panel have the highest appetite for your specific brand. This proactive approach ensures you’re in good hands before you ever lodge a formal application.
The core of your application rests on gathering the “Big Three” documents: the Franchise Agreement, the Disclosure Document, and the Lease. These must be paired with professional financial forecasts, including profit and loss projections and a data-backed business plan. Once these are ready, we manage the formal application process, including the credit assessment and any required valuations. Finally, we review the loan offer with you, sign the documents, and coordinate the final settlement to keep your launch on schedule.
Preparation: Before You Sign the Agreement
Successful funding starts long before you sign on the dotted line. You must seek specialised legal advice on the Franchise Agreement to identify any clauses that might act as lending hurdles. At the same time, you’ll need to organise your personal tax returns and BAS statements from the last two years to prove your financial stability. Lenders make a clear distinction between the initial Franchise Fee and the Total Investment Cost, which includes fit-outs and equipment. Knowing these figures exactly allows us to structure a deal that covers your entire capital requirement without straining your cash flow.
The Approval and Settlement Phase
Once your application is with a lender, it undergoes a “Common Sense Assessment” by a commercial credit team. They look beyond the spreadsheets to evaluate the logic of the deal and the strength of the brand. It’s common for lenders to issue conditions of approval, such as requiring life insurance or personal director guarantees. We act as your high-level fixer during this stage, coordinating between the franchisor, your solicitor, and the lender to ensure a stress-free handover. This collaborative effort is what ensures a seamless transition from applicant to business owner. If you’re ready to see what’s possible for your business dream, get started with an expert consultation today.
Why Partnering with a Specialist Broker is Your Best Move
Navigating the Australian lending market alone often leads to a cycle of rejection and frustration. While a single bank is limited by its own rigid credit policy, a franchise finance broker australia provides a strategic bridge to a vast landscape of capital. We act as a high-level fixer for complex deals that traditional lenders often struggle to categorise. By positioning your application correctly from the start, we ensure you stay in good hands, moving you from a state of uncertainty toward a feeling of streamlined confidence and relief.
The most significant advantage is our inside access to rates and terms that are never advertised to the general public. Because we manage a high volume of business acquisition funding, we hold influence that individual borrowers simply cannot replicate. Broker.com.au uses proprietary AI technology to analyse your specific deal against our lender panel, matching you with the institution most likely to favour your franchise brand and financial profile. This tech-driven approach removes the guesswork, allowing you to focus on your operational goals while we handle the heavy lifting of the finance application.
Access to a National Panel of Lenders
The Australian financial landscape is diverse, yet many prospective business owners limit themselves to the Big Four banks. While these institutions have their place, specialised commercial lenders are often hungrier for exposure to specific, high-performing franchise systems. One bank might say no due to an internal cap on a certain industry, whereas another lender on our national panel may be actively looking to grow their portfolio in that exact sector. We manage the M&A level complexity of these acquisitions, ensuring a seamless transition that protects your interests at every turn.
A Seamless, Tech-Driven Experience
Speed is a competitive advantage in business. Our proprietary technology streamlines the data-gathering process, allowing for faster submissions and quicker approvals. This efficiency doesn’t come at the cost of personal service; instead, it frees up our expert guides to provide the tailored advisory you need for a stress-free experience. You don’t have to manage the anxiety of dealing with multiple banks and conflicting requirements on your own. If you’re ready to secure the capital you need with an award-winning partner, let us know I’m interested to start a low-pressure conversation about your business dreams.
Secure Your Future with Strategic Franchise Funding
Launching a business is one of the most significant financial steps you’ll ever take. By understanding the nuances of the Australian lending landscape, you’ve already moved from a state of uncertainty toward streamlined confidence. Success lies in balancing the right capital structure, whether you’re leveraging property for lower rates or utilising unsecured business loans to protect your family home. Ensuring your lease terms and business plan align with lender expectations is critical for a stress-free approval process.
As an award-winning franchise finance broker australia, we provide the expert guidance needed to manage complex acquisitions and franchise fees. Our proprietary AI-powered lender matching ensures faster results by connecting your deal with the institution most likely to say yes. You don’t have to face these hurdles alone when you can have a high-level fixer by your side. We’re here to ensure you stay in good hands from your first enquiry to the final settlement day.
Ready to take the next step toward business ownership? I’m interested – Let’s discuss your franchise funding goals. Your dream of running a successful Australian franchise is within reach, and we’re excited to help you build it.
Frequently Asked Questions
Can I get funding to buy a franchise with no prior industry experience?
Yes, it’s possible to secure funding without direct industry experience, especially if you’re joining a Tier 1 franchise with comprehensive training programmes. Australian lenders look for transferable management skills and a strong personal financial position. While a lack of direct experience can be a hurdle, a professional business plan that highlights your operational expertise can bridge the gap. We often act as a high-level fixer to help present your case to the right lender.
How much deposit do I need for a franchise loan in Australia?
Most Australian lenders require a deposit of between 30% and 50% of the total purchase price. However, if you’re buying into an accredited franchise system, some banks may lend up to 70% of the acquisition cost. This capital contribution, often called “skin in the game,” proves your commitment to the business. A specialist franchise finance broker australia can help you identify which lenders offer the highest loan-to-value ratios for your specific brand.
What is the average interest rate for franchise finance in 2026?
As of August 2026, indicative interest rates for franchise finance typically range from 7.50% to 19.40% per annum. Your specific rate depends heavily on whether the loan is secured against property, the strength of the franchise brand, and your personal credit history. Secured loans generally sit at the lower end of this scale, while unsecured cash-flow lending attracts higher rates due to the increased risk the lender takes on without physical collateral.
Can I use my Self-Managed Super Fund (SMSF) to buy a franchise?
You cannot directly use an SMSF to purchase or operate a franchise business, as this would likely breach the “sole purpose test” and other ATO regulations. However, you can use your fund to acquire the commercial property from which the franchise operates. This complex area requires specialised SMSF loans and strict adherence to compliance rules. It’s essential to seek professional advice to ensure any property investment within your super fund remains legally compliant.
How long does it typically take to get a franchise loan approved?
Approval times vary significantly depending on the lender and the complexity of the deal. Traditional banks usually take between two to four weeks to process a formal application, provided all documents like the Franchise Agreement are ready. If you’re using fintech lenders for unsecured options, approvals can occur within 24 to 48 hours. Using our proprietary AI technology helps streamline this data-gathering phase, moving you toward a stress-free settlement much faster than traditional methods.
Is it possible to get a loan for a brand-new franchise system in Australia?
Securing finance for a brand-new franchise system is more challenging because there’s no historical data for lenders to review. Banks will scrutinise the franchisor’s professional background and the success of any pilot stores. You’ll likely need to provide additional security, such as residential property, to mitigate the risk. In these cases, working with a specialist broker is vital to find niche lenders who are willing to back emerging brands with strong growth potential.
What happens if the lender loan term is shorter than my franchise agreement?
Lenders generally require the loan term to be shorter than, or equal to, the length of your franchise agreement and commercial lease. If your loan term is shorter than the agreement, it simply means you’ll pay the debt off before your rights to the franchise expire. This is often viewed positively by credit teams as it improves your long-term equity. Problems usually only arise when the lease is shorter than the loan, which creates a significant risk.
Do I need to provide a personal guarantee for a franchise business loan?
Yes, most Australian lenders require personal guarantees from the directors when a business loan is taken out through a company or trust structure. This guarantee makes you personally liable for the debt if the business cannot meet its repayments. It’s a standard requirement that provides lenders with an extra layer of security. We help you understand these obligations clearly so you feel like you’re in good hands before signing any formal documents.
